
Arrow Options Turn Defensive as Stock Slides Into Earnings
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
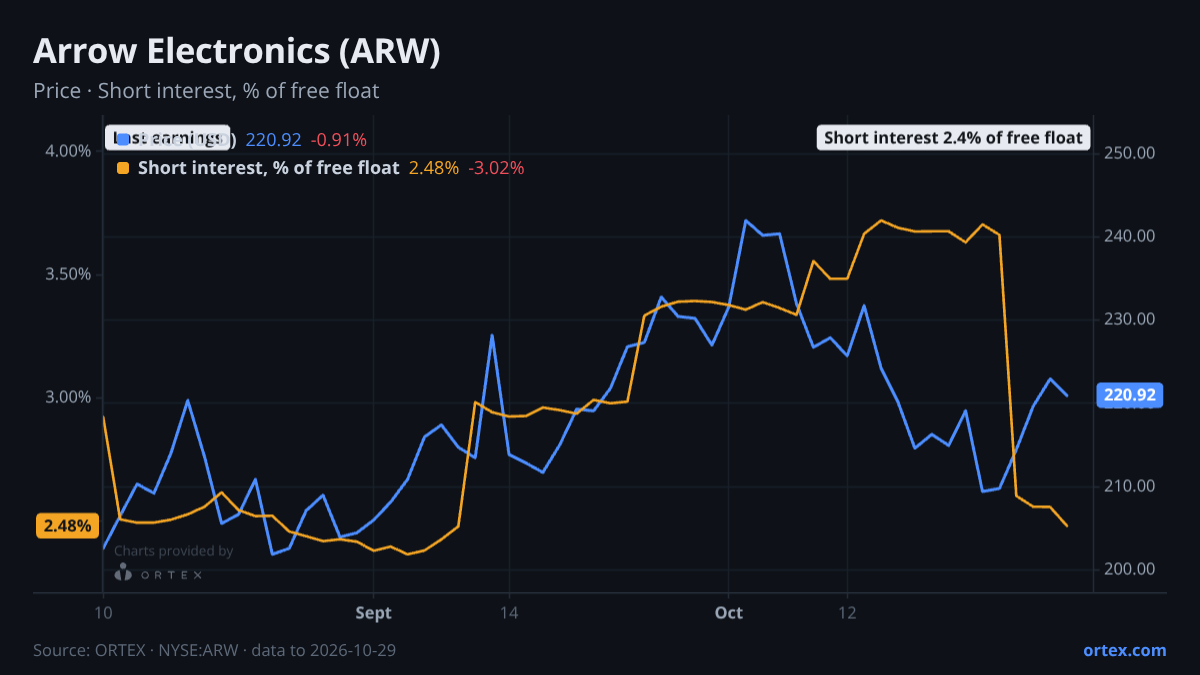
Arrow Electronics reports Q3 results on November 5 with options traders more cautious than they have been for most of this year.
The clearest signal heading into the print is in the options market. The put/call ratio has climbed to 0.90, nearly two standard deviations above its 20-day average of 0.71. That shift has been sharp and recent: through mid-October, the PCR was running below 0.65; it broke above 0.78 on October 22 and has stayed elevated since. The move coincides with a rough month for the stock, which has fallen nearly 10% in the past 30 days to $208.34, including a 5.7% single-session drop on October 30. Over the same period, close peers AVT shed only 0.14% on the week and LFUS gained nearly 12%, making Arrow's underperformance look company-specific rather than sector-wide.
The short-selling picture tells a contrasting story. Short interest has fallen sharply, dropping 32% over the past week to just 2.4% of the free float, one of the more notable week-on-week unwinds in the past year. The ORTEX short score has moved in step, dropping from 36 in mid-October to 32 by October 29, reflecting the reduced short positioning. Borrow costs remain negligible at 0.54%, and availability is exceptionally loose at 4,250%, meaning shares are easy to borrow for anyone who wants to add a short position. The lending market is not under pressure.
The analyst picture is split, though the most recent moves are now three months old. Wells Fargo kept an Underweight rating after Q2 results in August, raising its target to $200. Truist Securities held a Buy but trimmed its target to $250 from $260 on the same day. The mean price target of $235 sits about 13% above the current price, but with the stock at $208 and Wells Fargo's bear-case target at $200, the downside scenario is not far off. The bear argument centers on whether the cyclical components recovery is durable or driven by one-time inventory restocking. The bull case rests on a still-cheap valuation: the P/E multiple is below 9, and the earnings yield ranks in the 88th percentile of the ORTEX universe, with EV/EBITDA at 7.1.
Earnings history adds weight to the caution. The two most recent prints both produced sharp negative reactions, with the stock falling roughly 9% and 10% on the day in each case. The print on November 5 will test whether Arrow's valuation discount is enough to absorb another miss, or whether the options hedging already in place reflects a well-calibrated read on the risk.
Against its own history
This week's change in short interest is 3.7 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -0.7% over the past week against a median of +1.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ARW on ORTEX →How this article was generated
- Generated
- 2 Nov 2026, 04:07
- Data as of
- 2 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.