
HWM Rebounds 10% in a Week After Pre-Earnings Sell-Off
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
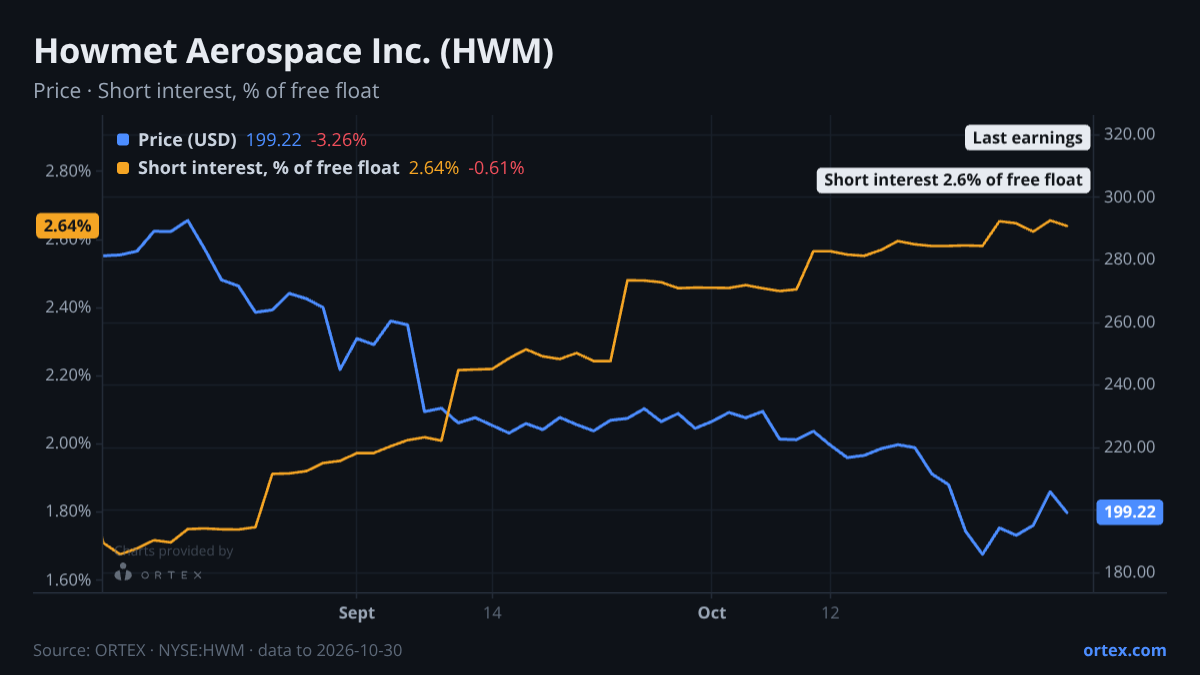
Howmet Aerospace has recovered sharply from its late-October collapse, gaining 9.6% over the past week to close at $212.99, a reversal that puts the November 6 print in an entirely different context from the one described in our October 26 preview.
The week's move stands out against the peer group. GE gained 9.5% over the same period, making it the only close peer to match HWM's pace. WWD added 4.6%, HXL 1.9%, and CW 1.6%. RTX gained 2.7%. The broader context matters: HWM fell 16% in the week before its October 29 report, then posted a 2% gain on the day of that print. The stock spent the following week clawing back much of the pre-earnings loss. Even after the recovery, HWM is still down roughly 8% over the past month, meaning the bounce has not yet erased the damage.
Options positioning has grown more defensive as the stock has recovered. The put/call ratio moved to 1.73 on November 2, above its 20-day average of 1.54 and approaching the 52-week high of 1.83. That is a notable shift: options traders were buying protection even as the underlying stock rose, which suggests uncertainty about the upcoming print rather than outright conviction in the direction of the move. The borrow market remains entirely untroubled. Availability is effectively unlimited, borrowing costs have fallen to 0.23%, and short interest is only 2.6% of the free float. The short score of 33.5 is in the middle of the range, consistent with where it has been for weeks.
The analyst community cut targets aggressively in the days surrounding the October 29 report, with every firm maintaining its rating while reducing its price. Jefferies lowered its target to $350 from $370 on November 2. BTIG went to $280 from $340. UBS, holding a Neutral, moved to $230 from $255. The mean target across 16 buy ratings and 2 holds is $296, roughly 39% above the current price. The bull case centres on engine and fastener demand from commercial aerospace OEMs, aftermarket spares growth and AI-driven gas turbine orders. First-half 2026 spares revenue rose 37% year-on-year to around $560 million, and full-year guidance was lifted to $10.05 billion of revenue. Bears point to concentration risk: roughly 70% of sales are tied to aircraft build rates that the company does not control, and Boeing disruptions, titanium supply constraints and tariffs have repeatedly delayed the conversion of that demand into reported revenue.
The ORTEX alt data layer flags that Howmet's remaining buyback authorization was up 208% year-on-year in Q4 2024, the largest on record since 2021. That is a capital-allocation signal, not a revenue lead, but it frames the shareholder return story that management is likely to discuss alongside the quarterly figures. The November 6 print will test whether the third-quarter revenue and margin delivery is strong enough to support a price that has bounced hard from oversold levels, or whether the broad target cuts from the analyst community reflect a view that the recovery has moved too far ahead of the fundamentals.
Against its peers
Shares moved +9.6% over the past week against a median of +1.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open HWM on ORTEX →How this article was generated
- Generated
- 3 Nov 2026, 05:20
- Data as of
- 3 Nov 2026, 04:14
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.