
Booking Holdings Reports Today as Short Sellers Beat a Retreat
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
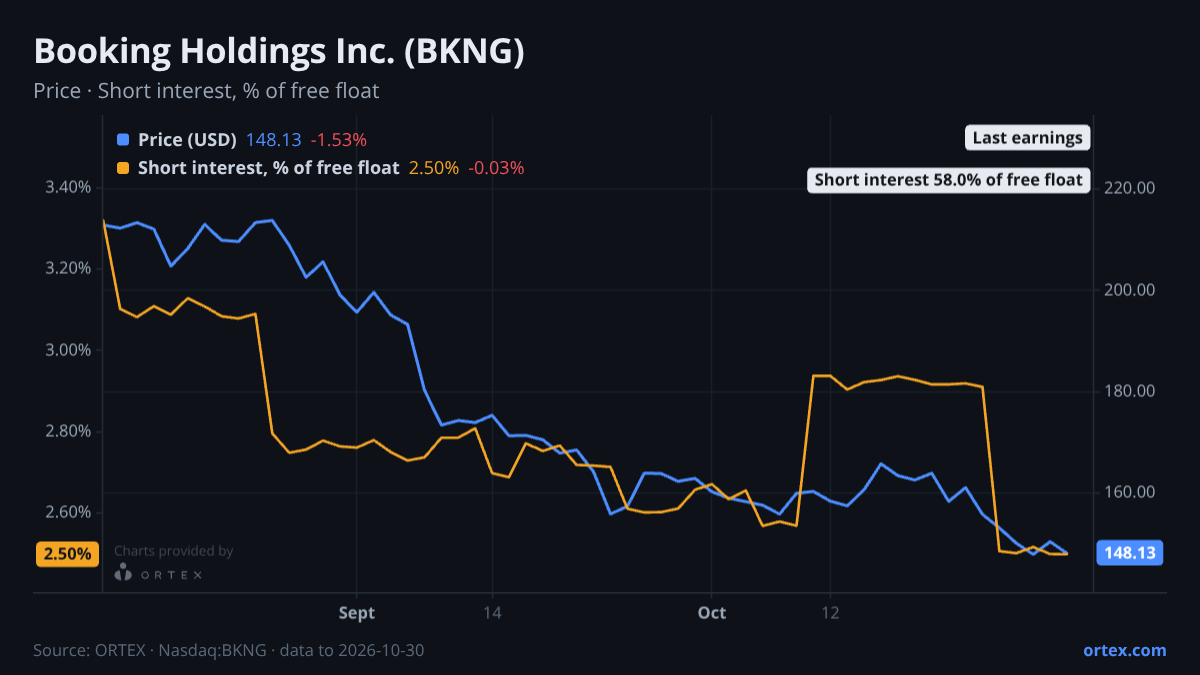
Booking Holdings reports Q3 results this evening, with the stock at $153.75, down 3.3% over the past month but up 3.8% on Monday alone. The setup is less tense than the price history might suggest: short sellers have been cutting exposure sharply, the borrow market is almost entirely relaxed, and options traders have turned notably more bullish in recent days.
The most striking positioning shift is in short interest. At 58% of the free float, the headline figure looks alarming, but the direction tells a different story: shorts fell 14.4% over the past week, with the bulk of that drop occurring between October 22 and October 24 when nearly 3 million shares were covered in a single step. The ORTEX short score has also declined from 34 to 32.5 over the past ten sessions, reflecting easing pressure rather than accumulation. Borrow conditions confirm the same read: availability is effectively unconstrained, with more than 658 million shares available to borrow against roughly 18.7 million currently short, and the cost to borrow a negligible 0.36%. There is no squeeze dynamic here and no evidence of aggressive new short-selling into the print.
Options positioning reinforces the shift in sentiment. The put/call ratio dropped to 0.79 on Monday, more than 2.5 standard deviations below its 20-day average of 0.83. That is the lowest defensive reading in the past year, meaning traders have been buying calls at an unusually high rate relative to puts. The recent price move higher, combined with collapsing put demand, points to a repositioning toward the upside rather than a defensive hedge.
The analyst community is more divided. Bulls argue that Booking's mid-30s EBITDA margin, roughly 90% free cash flow conversion, and over $1 billion of net cash make it structurally resilient, with the Genius loyalty programme and direct traffic share reinforcing its competitive position in a fragmented market. Bears point to softer October booking data, exposure to France (estimated near 10% of global listings) and the Middle East (around 7% of room nights), and rising concern that AI-driven travel planning tools could erode the company's role as an intermediary over time. Recent analyst moves lean cautious on valuation: Cantor Fitzgerald cut its target from $220 to $170 in mid-October, and Wells Fargo trimmed from $220 to $190, both while keeping neutral ratings. The consensus target of $232 sits well above the current price, though that gap reflects where the stock was trading earlier in the year rather than fresh conviction. Morgan Stanley assumed coverage in September with an Overweight rating at $230, one of the more constructive recent inputs.
Wikipedia attention for Booking has climbed to 2.3 standard deviations above its own 90-day average, according to Wikimedia Foundation page-view data tracked by ORTEX. That reflects elevated retail interest heading into the release, though it is an attention measure rather than a revenue indicator.
After the prior quarter's print in August, the stock gained 7.4% on the day and 10.5% over the following five days, the clearest recent benchmark for what a clean beat can do. Tonight's report is less a test of whether the travel recovery is intact and more a question of whether management's guidance for Q4 room nights can absorb the geopolitical headwinds that have dominated the bear case since September.
Against its peers
Shares moved +0.4% over the past week against a median of -0.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open BKNG on ORTEX →How this article was generated
- Generated
- 3 Nov 2026, 05:29
- Data as of
- 3 Nov 2026, 04:28
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.