
Huron Consulting Shorts Surge to a Year-High After Earnings
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
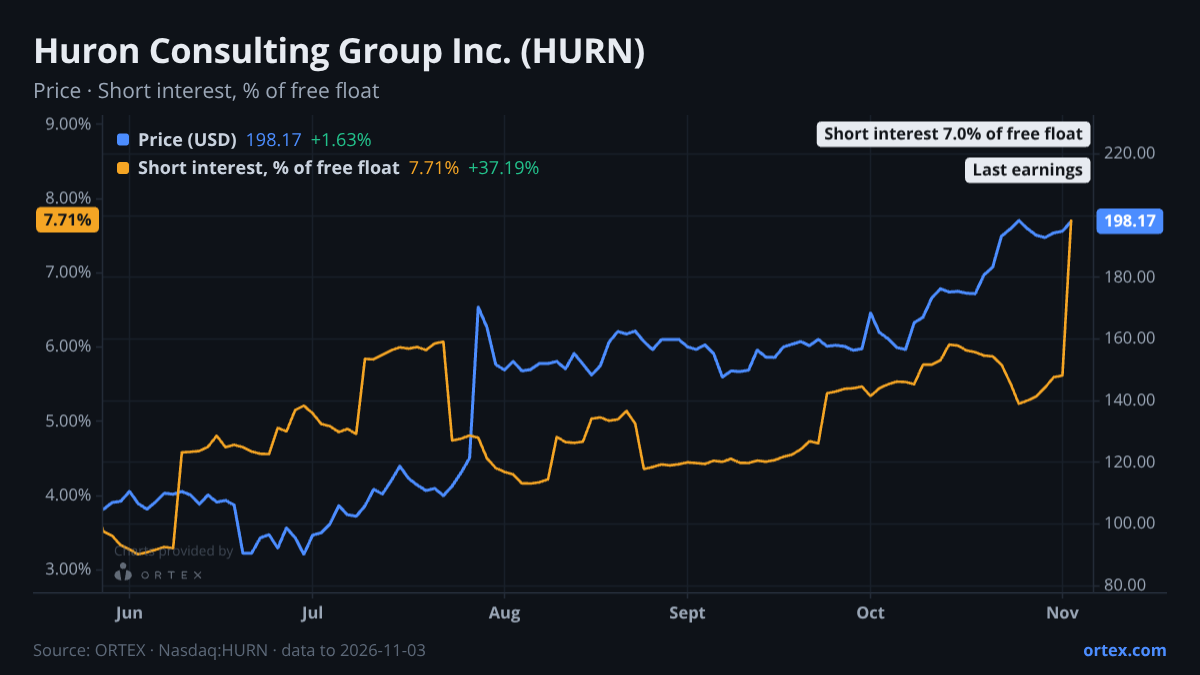
HURN is the most shorted name among its closest peers right now, and the gap opened sharply this week.
Short interest in Huron Consulting Group jumped 47% over the past week to reach 7% of the free float, the highest reading in at least a year. That move is roughly 4.1 standard deviations above HURN's typical weekly change, making it one of the most statistically unusual positioning shifts the stock has seen. By comparison, closest peer EXLS finished the week up 2.9% with no comparable short-side activity. CBZ and G each moved less than 3% on the week. Within the consulting and professional services group, HURN is now meaningfully more crowded on the short side than any of its correlated peers.
The short-interest move alone would warrant attention, but the lending market complicates the read. Availability has tightened sharply in the past two sessions: a ratio of available-to-borrow shares against shares already borrowed fell from 1,176% on November 2 to 463% on November 3, its lowest reading in the 52-week window. That still represents a comfortably supplied borrow market, far from any squeeze threshold, and cost to borrow has actually eased over the past month to 0.43%, well within the range that characterises a low-friction short. What the data shows is a sudden spike in demand for borrows rather than any constraint on supply. Options traders are running in the same direction: the put/call ratio is 2.26, more than 2.3 standard deviations above its 20-day average of 0.90. The options market shifted in one session on October 29, when the PCR jumped from 0.70 to 2.28 and has stayed elevated since. That is consistent with fresh hedging demand, not a gradual drift.
The timing is explained by earnings. Huron reported Q3 results on November 3, and two analysts moved their price targets materially higher in its wake. Wedbush raised its target from $160 to $220 on November 4, maintaining an Outperform rating. Truist Securities did the same in October, lifting from $175 to $220 with a Buy. Both targets sit above the current price of $198.17, leaving implied upside against the consensus mean of $202. The bull case rests on non-discretionary demand in healthcare and education, with management guiding to 2026 revenue of $1.78 billion to $1.86 billion and adjusted EBITDA margins of 14.5% to 15.0%. The bear case is harder to dismiss: operating income margin of 8.2% missed expectations at the last report, cash flow from operations turned deeply negative at minus $162 million, and EV/NTM EBITDA has compressed from 14.3x at the start of the year to 11.3x now. Factor scores are mixed at best, with EPS momentum in the 66th percentile but the short-score rank at just the 30th percentile and dividend score near the bottom of the universe at 28.
One institutional data point adds texture. ORTEX Alt Data flags that Wikipedia and ORTEX page-view attention for HURN is running at a z-score of 2.24 relative to its own 90-day history as of October 20, the highest retail-attention reading in that window. This is an attention measure, not a revenue indicator, but the spike in public interest aligns with the week's earnings release and the analyst target revisions that followed.
Insider activity in the recent window is worth noting only in its direction. Net selling over the past 90 days totalled roughly $4.4 million, with the CEO conducting planned 10b5-1 sales in late July. The Chief Accounting Officer sold in a discretionary transaction in late July as well. Neither is unusual for a stock that has gained 22% over the past month, and neither is recent enough to change the current story. Among institutional holders, BlackRock added 74,753 shares in Q3, lifting its stake to 9.3% of shares outstanding. Principal Global Investors added 144,823 shares in the same period, a more pronounced increase for a smaller starting position. No 13D activist is on the register.
The level to watch is whether short interest can hold above 7% of float once the post-earnings dust settles. At current borrow costs and availability, adding to or maintaining short positions carries little friction. The question is whether the fundamental concerns around cash conversion and margin carry enough weight to sustain that positioning against two analysts now targeting $220.
Against its own history
This week's change in short interest is 4.1 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved +1.2% over the past week against a median of +0.6% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open HURN on ORTEX →How this article was generated
- Generated
- 4 Nov 2026, 19:18
- Data as of
- 4 Nov 2026, 19:09
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.