
Swire Pacific Eyes Results with Borrow Costs Easing
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
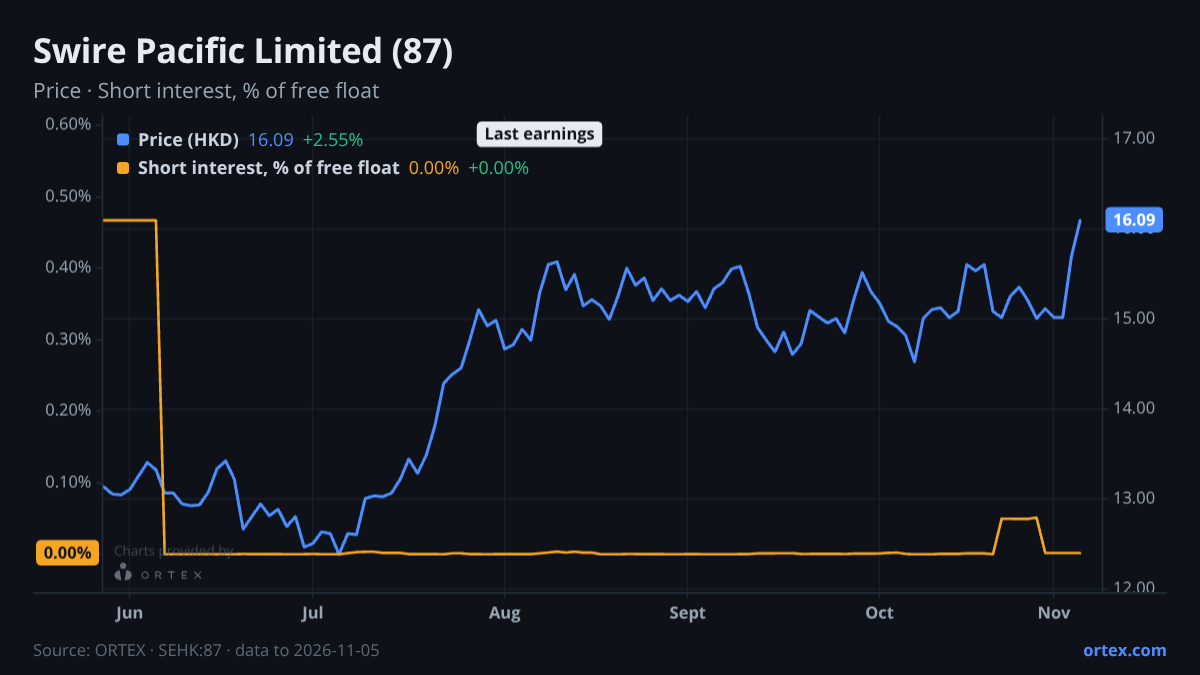
Swire Pacific heads into its November 13 interim results with the stock up 6% on the week and borrowing costs on a steady retreat, a relatively calm setup for a conglomerate that rarely sits still.
The clearest story in the lending market is the direction of travel on cost to borrow. After running above 12% through much of the summer, the annualised rate has eased to just above 10%, a four-month low. Availability is essentially unconstrained, with roughly 88 million shares available to lend and only a fraction of those currently out on loan. The sharp drop in reported short shares over the past week (down more than 96% week-on-week from a brief spike around October 29) looks more like a data artefact from the daily estimate series than a meaningful short-covering event. The underlying picture is one of little bearish conviction: shorts are not building, borrow is loosening, and there is no meaningful squeeze dynamic in play.
Where the data is more interesting is in the factor score profile. The dividend score ranks in the 86th percentile of the ORTEX universe, reflecting Swire Pacific's history as a yield-oriented holding. The 90-day forward EPS momentum score, at the 75th percentile, suggests analysts have been lifting estimates at a pace well above average over the past quarter. The short score of 30.3 is low and has been drifting lower over the past week from 31.4, consistent with the easing borrow conditions. The earnings yield factor ranks in the 68th percentile. That combination, decent yield, rising estimates, low short score, is a reasonable summary of why value-oriented institutions have held the name. The EV figure in the valuation data is flagged as of December 2025 and should not be treated as current. No recent analyst changes are available to sharpen the directional picture.
The ownership structure is as concentrated as ever. John Swire and Sons holds just under 56% of the shares. BlackRock added roughly 5.7 million shares in the quarter to September, bringing its stake to just under 2.8% of shares. The insider trade data in the snapshot is stale, all activity from 2024 and earlier, so no current signal can be drawn from it.
Earnings history shows the stock moved 5.7% on the day of the August 2026 interim release and held most of that gain over the following week. The print on November 13 is the next scheduled catalyst. With borrow loose, shorts not building, and the stock already up 7% over the past month, the market appears to have positioned ahead of that event rather than remaining on the sidelines.
What to watch next: whether the November 13 results confirm the upward EPS estimate revision implied by the 90-day momentum score, and whether cost to borrow continues its gradual descent or stabilises near the current 10% level in response to any post-earnings repositioning.
Stocks in this article
See the live data behind this article on ORTEX.
Open 87 on ORTEX →How this article was generated
- Generated
- 7 Nov 2026, 17:32
- Data as of
- 7 Nov 2026, 17:32
- Prompt version
- v1.0
- Data sources
- Short interestUtilizationEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notes
- Validation notes
- soft: missing section mentions: short interest (informational only)
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.