
Sysco Drops 4% in a Week, But the Acquisition Debate Dominates
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
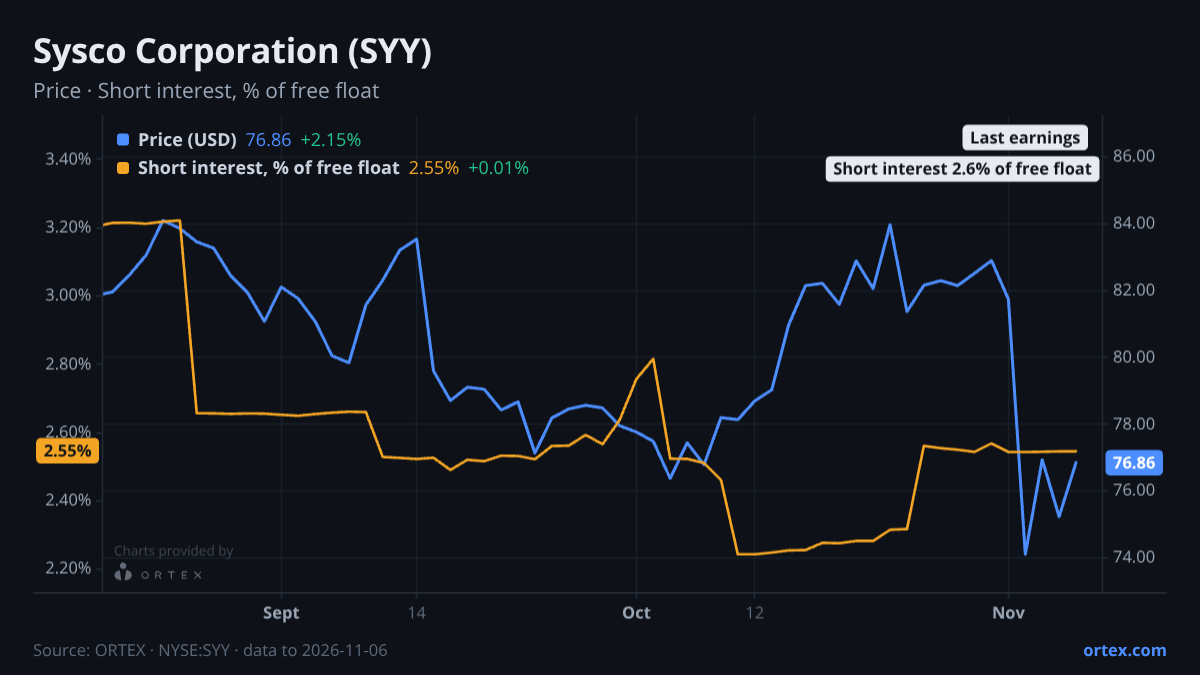
SYY fell 4.1% over the past week to $78.38, underperforming its closest foodservice peers by a wide margin. PFGC gained 10.8% over the same period and USFD added 3.9%, making Sysco the clear laggard in the group ahead of its November 13 results. Short interest, at 2.6% of the free float, remains low and has barely moved. The lending market reflects the same indifference: availability is effectively unlimited, with nearly 490 million shares available to borrow and cost to borrow at just 0.37%, down sharply on the week. Options traders are equally relaxed. The put/call ratio of 0.36 is barely above its 20-day average and sits well below the 52-week high of 0.52, with a z-score near zero. The positioning story, in short, is not about short sellers or hedgers. It is about fundamental disagreement over a single deal.
The Restaurant Depot acquisition is what divides the Street. The bull case is that the cash-and-carry channel adds meaningful revenue and EBITDA, with the combined business trading at roughly 10x forward EBITDA. At that multiple, the argument runs, the market is not paying a premium for execution risk. Citigroup's Karen Holthouse cut her target to $84 from $87 on November 5 while keeping a Neutral rating, the most recent Street move. Morgan Stanley lifted its target to $91 in October, and JP Morgan held Overweight despite trimming to $95 from $100 in late September. The consensus mean target is $91.75, against a current price of $78.38, implying meaningful upside. The bear case is more structural: a deal done at a valuation premium to Sysco's own equity multiple, pro forma leverage of 4.6x, and a foodservice demand backdrop that remains soft. Buyback data from the ORTEX Alt Data layer adds a note of caution: Sysco's SEC-reported buyback spend in Q2 2026 was zero, the smallest Q2 figure in three years.
A director, Thomas Gerard Ondrof, made an open-market purchase of 2,500 shares at $76.62 on November 4, a modest but discretionary bet placed just days before the print. It was not made under a 10b5-1 plan. Net insider activity over the past 90 days is modestly negative at around negative $1.1 million, mostly driven by compensation-related grants rather than open-market sales, so the overall tone from insiders is closer to neutral than bearish. BlackRock remains the largest institutional holder at 8.7% of shares, with Harris Associates the most notable recent mover, adding over five million shares as of September 30.
The November 13 print is less a test of Sysco's core distribution business and more a first real look at how management frames the Restaurant Depot integration, its cost trajectory, and whether the EBITDA outlook for the combined entity holds up against a backdrop that sent the stock lower while peers rallied.
Against its peers
Shares moved -4.1% over the past week against a median of +0.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open SYY on ORTEX →How this article was generated
- Generated
- 10 Nov 2026, 04:07
- Data as of
- 10 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.