
Humana Shorts Retreat After Earnings Beat, Analysts Raise Targets in Unison
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
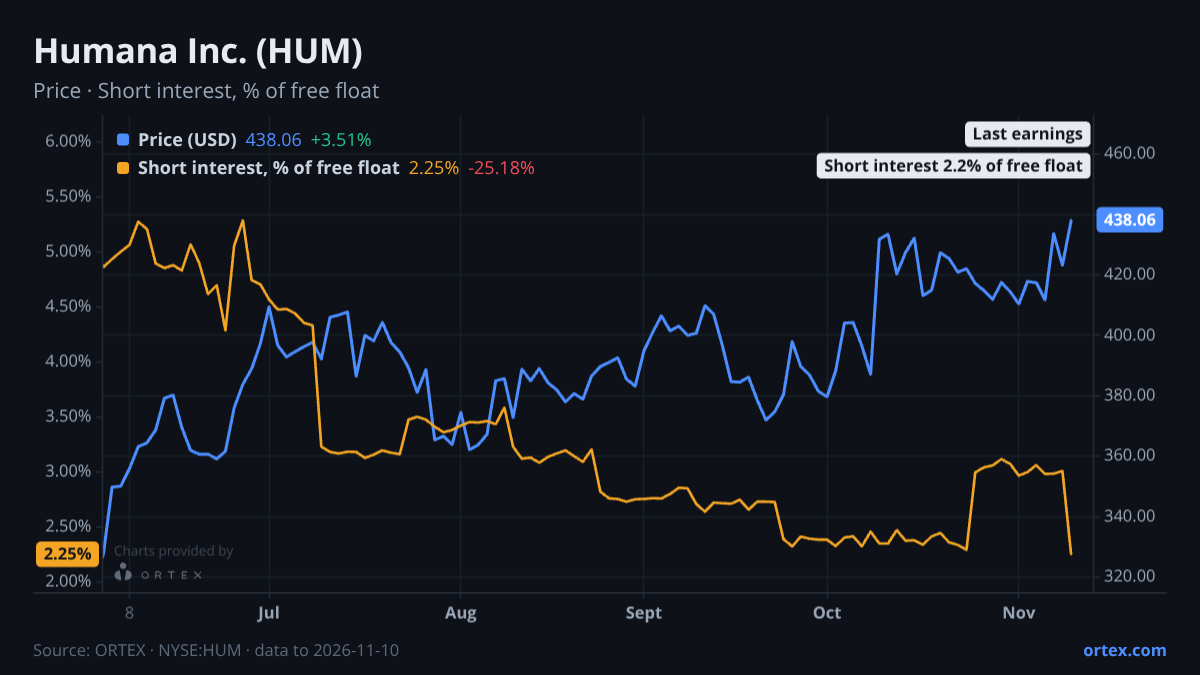
Humana posted its Q3 results on November 6 and the short position that had been building at a 3.7-sigma pace ahead of that print has since collapsed, with short interest dropping 25% in a single session on November 10 to 2.24% of the free float, the lowest level in at least a year.
The retreat in short positioning is dramatic by any measure. Heading into earnings, shorts had pushed their position from roughly 2.75 million shares to above 3.6 million in under a week. By November 10, that figure had unwound to 2.70 million. The move is 2.8 standard deviations below Humana's typical weekly swing, putting it at the opposite extreme from the pre-earnings build. The borrow market was never under pressure through any of this: availability remains extraordinarily loose at 9,243%, meaning roughly 92 shares are available to lend for every one currently borrowed, and the cost to borrow at 0.26% has fallen 26% over the week. There is no friction in the lending pool for anyone who wants to establish or cover a short position.
Options positioning tells a more cautious story, and the two signals diverge in a way worth noting. The put/call ratio reached 1.18 on November 10, near its 52-week high of 1.19 and running above its 20-day average of 1.11. The z-score of 0.85 is not extreme, but the ratio has been trending higher since mid-October, moving from the low 0.90s to the upper 1.10s consistently. Shorts may be covering, but options traders are still carrying more downside protection than usual.
The analyst response to the Q3 print was uniformly positive and notable in its scale. JP Morgan's Lisa Gill raised her target from $393 to $484 on November 10, maintaining a Neutral rating but effectively marking a $91 upgrade to her price framework. Piper Sandler and Guggenheim both lifted targets above $520 while holding Overweight and Buy ratings respectively. Barclays nudged its target higher to $587, the highest on the Street. Even the sceptics moved: TD Cowen raised from $370 to $430 while staying at Hold. The mean price target now stands at $483, against a current price of $438, implying roughly 10% upside to consensus. The stock's forward earnings revision rank sits at the 95th percentile of the universe, and the analyst recommendation differential ranks at the 94th percentile, reflecting broad but not unanimous conviction. The bull case centres on 500 basis points of margin improvement in Group Medicare Advantage and CenterWell's 16% revenue growth. The bear case has not gone away: a $3.5 billion headwind from declining Star ratings and the associated roughly $22 EPS drag for 2026 remain on the table, alongside rising competition in Medicare Advantage.
Humana's performance this week also stood out against peers. The stock gained 4.8% over the five sessions, against a median of around 3.2% for its closest managed care peers. CNC added 4.0% and ELV rose 3.8%, while UNH barely moved at 0.2%. MOH slipped 0.7%. The outperformance reflects a Humana-specific catalyst, the earnings print, rather than a sector-wide re-rating.
The ORTEX short score dropped sharply to 30.9 on November 10, down from readings above 33 all week. That places Humana in the lower half of its peer universe on bearish pressure. The alt data layer flags a retail attention pickup, with Wikipedia and ORTEX page views running 1.7 standard deviations above Humana's own 90-day baseline as of October 23, consistent with an earnings-driven interest spike. The buyback data offers one muted note: Humana spent $1 million on repurchases in Q2, down 99% from a year earlier and the smallest Q2 buyback in six years, suggesting capital allocation priorities have shifted during a period of strategic restructuring.
The next earnings event is scheduled for February 10, 2027, giving the market 91 days to assess whether the Star ratings headwind materialises as feared or whether the margin recovery story continues to run. The price level to watch is $484, where JP Morgan now anchors its neutral case and where consensus targets cluster most densely.
Against its own history
This week's change in short interest is 2.8 standard deviations below the company's typical weekly move over the past year. Short interest is at its lowest level in at least a year.
Against its peers
Shares moved +4.8% over the past week against a median of +3.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open HUM on ORTEX →How this article was generated
- Generated
- 11 Nov 2026, 18:25
- Data as of
- 11 Nov 2026, 18:19
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.