
Replimune Reports Thursday With Shorts at 32% of Float and Options Turning Defensive
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
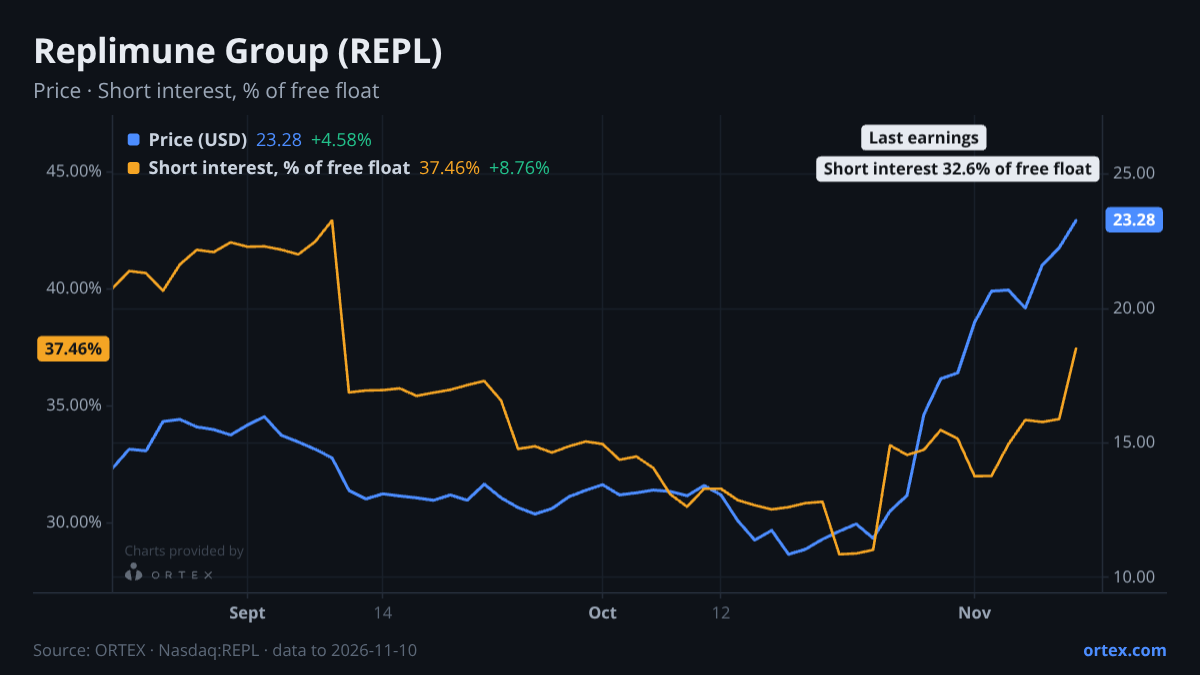
Replimune Group reports fiscal second-quarter results on November 13, one day after a 6.4% pullback brought the stock to $21.78, capping a month in which shares still gained 62%.
Short positioning is the most striking feature of the setup. More than one in three shares in the free float is now sold short, with short interest at 32.6% of float after rising 17% over the past week and 8.8% in a single session on November 10. That weekly move runs roughly 1.7 standard deviations above Replimune's own historical pace, meaning the recent buildup is unusually fast even by this stock's standards. The ORTEX short score reached 64.1 on November 10, its highest reading in the recent window. Yet the borrow market has not tightened to match: availability remains at 733%, meaning far more shares are on offer to lend than are currently borrowed, and the cost to borrow is just 0.43%, down 12% over the past month. Shorts are adding aggressively, cheaply, and without friction.
Options positioning has shifted in the same direction. The put/call ratio is running at 0.46, more than two standard deviations above its 20-day average of 0.27, its highest defensive skew in several weeks. That is a material change: a month ago the ratio sat below 0.20, well inside normal territory. The two signals, heavy short interest and a sudden jump in put demand, are pointing the same way into the print.
The fundamental debate centres on RP1, the company's lead oncolytic immunotherapy. The bull case rests on the BLA resubmission for RP1 plus nivolumab in advanced melanoma, where a different review team raises hopes for a more favourable outcome, and on clinical data showing no negative impact from biopsies or surgical interventions on tumour response. Bears point to the FDA's request for a meeting over the trial design of the Phase 3 IGNYTE-3 study, with an interim overall survival readout not expected until 2027. That delay puts pressure on the cash runway and raises questions about whether the company can fund both the ongoing trial and next-generation RP2 development without restructuring. Leerink Partners raised its target from $19 to $31 after the most recent quarterly update at the end of October, maintaining an Outperform rating. The consensus mean target of $23.33 is now modestly above the current price, leaving limited implied upside on the Street's central view despite the bullish tone from some firms.
Baker Bros. Advisors, the most prominent activist holder on the register, filed a Schedule 13D/A in August disclosing a stake of 11.8%, down from 14.3% previously. That reduction is worth noting: an activist trimming while still holding above 10% is not an exit, but it is a signal the position has been reworked. Ridgeback Capital and Montanova Capital both appear to have built new or substantially larger positions this year, each holding above 7% as of their last disclosures. Goldman Sachs filed a 13G/A on November 9, reducing its disclosed stake from 5.3% to 3.3%, crossing below the routine reporting threshold. Stakes are as last disclosed around the 5% threshold, and holders dropping below 5% may not file again. ORTEX also forecasts a 69% probability that Replimune joins several MSCI indices, including the MSCI World Small and MSCI USA IMI, at the November 2026 quarterly review, with a trade date of November 30 and an effective date of December 1. At $21.78, the stock is 7.5% above the price line that decides inclusion, which stands at $20.60. Combined passive buying flows across the forecasted additions amount to roughly $291M, equivalent to around four days of normal volume. These are ORTEX forecasts, not announcements from the index provider.
Thursday's print is therefore less a test of near-term revenues and more a test of whether the BLA path for RP1 has cleared enough of the FDA's concerns to give the market confidence in a 2027 approval, and whether the cash position is sufficient to sustain the pipeline without forced dilution.
Against its own history
This week's change in short interest is 1.7 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +5.3% over the past week against a median of +1.8% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open REPL on ORTEX →How this article was generated
- Generated
- 12 Nov 2026, 04:13
- Data as of
- 12 Nov 2026, 03:54
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataIndex RebalancePrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.