
Wells Fargo Upgrades Ecolab the Day Before the Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
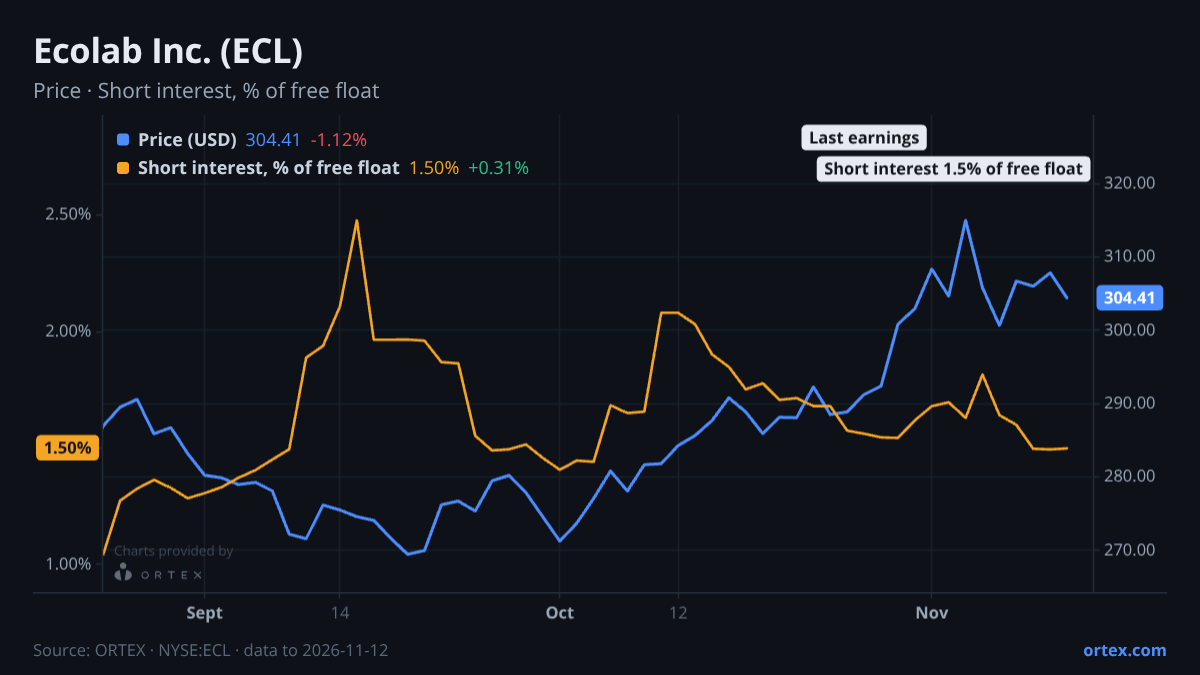
ECL gained 2.9% over the past week to close at $309.27, outpacing a median gain of 0.2% across its closest specialty chemicals peers. The catalyst sharpening that gap landed yesterday: Wells Fargo's Jason Haas upgraded the stock to Overweight from Equal-Weight and lifted his target from $315 to $380, a move that changes the analyst narrative materially just 24 hours before the Q3 results.
The upgrade is the most significant shift in a broader wave of post-results analyst revisions. Following Q3 earnings on October 27, UBS raised its target to $357, Citigroup moved to $345, and JPMorgan edged up to $310, all while maintaining existing positive ratings. What changed with the Wells Fargo move is the rating itself, not just the target. Haas had sat on the sidelines at Equal-Weight for months, raising his target incrementally from $275 to $295 to $315 through the year. The jump to $380 and Overweight in a single step, the day before the November 17 report, is a material repositioning. The stock at $309.27 now trades above JPMorgan's $310 target but well below the $357 to $380 range set by the more bullish houses, leaving a wide spread for the print to arbitrate.
The bull case rests on Ecolab's pricing power and the expansion of its high-tech segment, with Global High-Tech revenue running at nearly $1.5 billion annualised in FY26, tied to AI infrastructure buildout through the CoolIT and Ovivo acquisitions. Management has guided for 14% to 15% base-business EPS growth in the second half of 2026, and the forward earnings upgrade cycle, while decelerating, still ranks in the 78th percentile on a 12-month forward basis. The bear case is simpler: at a trailing P/E of around 33 and an EV/EBITDA of 19, the stock prices in a lot of execution. Any shortfall on organic volume growth, which ran at just 1% recently, or margin progression toward the guided 19% FY26 target, would stress a multiple that already sits well above peers like SHW and PPG.
Short positioning offers little additional signal here. Short interest has fallen roughly 9% over the past month to 1.5% of the free float, a low level with no meaningful short pressure. Borrow availability is exceptionally loose, with more than 162 million shares available relative to around 4.2 million sold short. Cost to borrow is 0.52%, close to the cheapest it has been all year. One insider trade worth noting: director David MacLennan bought 600 shares in the open market on November 12 at $308.13, a modest but unplanned purchase just two trading days before the report.
The November 17 print will test whether Ecolab's margin trajectory and organic volume trends justify the premium the upgraded analyst community has now assigned it, and whether Wells Fargo's late-arriving conviction was timed correctly or prematurely.
Against its peers
Shares moved +2.9% over the past week against a median of +0.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ECL on ORTEX →How this article was generated
- Generated
- 14 Nov 2026, 04:02
- Data as of
- 14 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.