
Target Options Turn Defensive Before Tuesday's Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
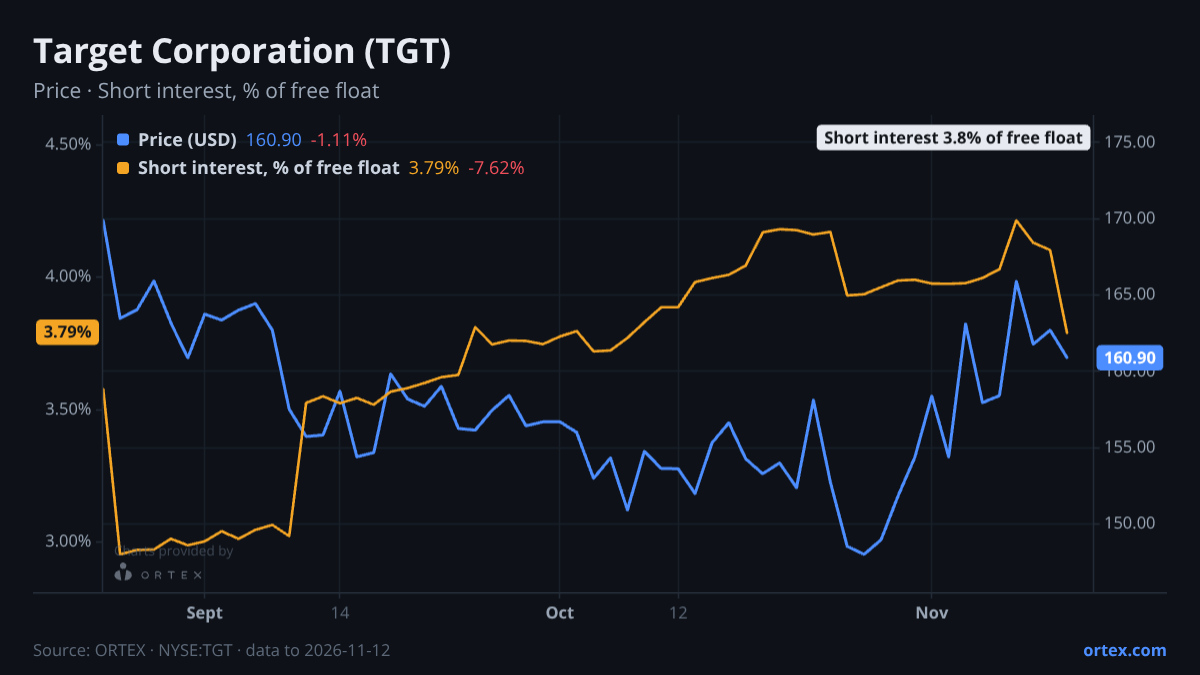
Options traders have adopted their most cautious stance toward TGT in almost a year. The put/call ratio reached 1.15 on Thursday, nearly two standard deviations above its 20-day average of 0.99. That is close to the 52-week high of 1.16, a level briefly touched earlier this week. The shift arrived as the stock gained 1.9% over the past week to close at $161.45, outpacing a median decline of around 0.2% across its closest peers: DG fell 2.5% over the same period and GO dropped 2.2%. Short interest at 3.8% of the float is modest and fell sharply, down 7.6% in a single session on November 12 and nearly 5% on the week. Borrow availability remains extremely loose at over 1,200% of short interest, meaning the lending pool is barely touched. The cost to borrow has edged up 25% over the past week but remains negligible at 0.54%, so there is no short-side pressure story here.
The debate heading into the print centres on whether Target's turnaround is durable or still too reliant on a consumer environment that tariffs and inflation could quickly erode. The bull case rests on the Q2 print that showed comps rising 3.8%, traffic up 3.6%, and management lifting full-year EPS guidance to $9.90 to $10.90. UBS reinforced that view on November 12, raising its target to $205 and maintaining its Buy rating. Guggenheim reiterated Buy at $175 on the same day. The bear case points to heavy tariff exposure across apparel and home categories, the 97%-plus share of sales fulfilled through physical stores limiting structural flexibility, and the risk that consumer sentiment deteriorates faster than the company's improving private-label mix and digital capabilities can offset. JP Morgan sits in the middle, lifting its target to $163 from $157 on November 9 while keeping a Neutral rating, essentially arguing the stock is fairly valued at current levels even after the year-to-date gain of roughly 64%.
Insider activity in the 90 days to end-October leaned decisively toward selling. CEO Brian Cornell sold 50,000 shares in late August at around $163.56, raising approximately $8.2 million. CFO Melissa Kremer sold 15,500 shares around the same time at roughly $170, netting about $2.6 million. Neither sale was declared under a 10b5-1 pre-arranged plan, which makes them more directly read as discretionary. Net insider transactions over the period came to roughly negative $11 million in value. That cluster of executive sales just above the current price is an overhang the bulls will need the print to push past.
Tuesday's report will test whether Q2's broad-based volume recovery extended into Q3, and whether Target can hold gross margin as tariff costs bite into the discretionary and apparel categories that sit furthest from its grocery anchor.
Against its peers
Shares moved +1.9% over the past week against a median of -0.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open TGT on ORTEX →How this article was generated
- Generated
- 14 Nov 2026, 04:03
- Data as of
- 14 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.