
Progressive Faces Its Print With Shorts Rising and Insiders Selling
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
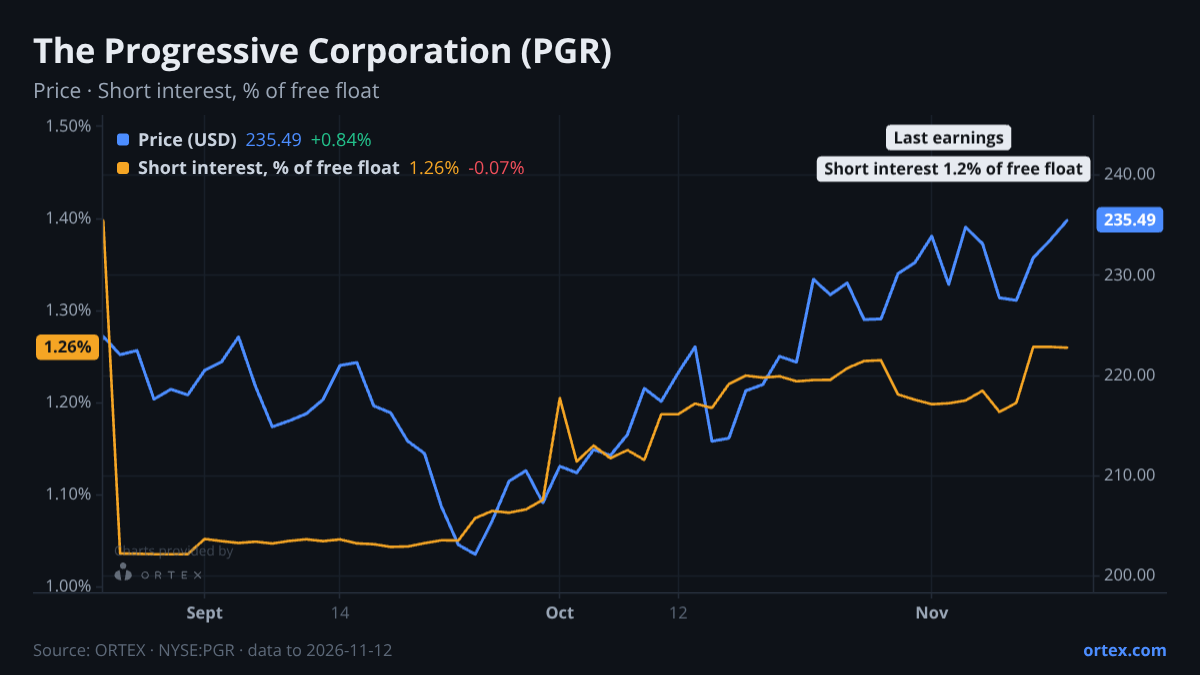
PGR has gained 3.5% over the past week to $235.78, outpacing the median 2.1% rise among its closest insurance peers, with ALL up 5.0%, UVE adding 3.9%, and ACGL gaining 2.2%. That relative strength comes into Tuesday's earnings release despite a lending market that offers no short-side signal worth watching: availability is essentially unlimited, borrowing costs have dropped 30% over the past week to just 0.34%, and short interest at 1.2% of the free float is too thin to generate squeeze dynamics in either direction. Options positioning is similarly calm, with the put/call ratio at 0.88, fractionally below its 20-day average of 0.89.
The more pointed data is in insider activity. Every sale in the past 90 days was executed under a pre-arranged 10b5-1 plan, so each trade reflects a scheduled disposal rather than a discretionary call on the stock. That said, the volume is not trivial: net insider selling totalled roughly 48,000 shares worth $10.5 million over the period, with CEO Susan Griffith accounting for the largest single transactions, 37,338 shares on September 1 at $219.50 and again on July 27 at $212.71. CFO Andrew Quigg and several divisional presidents also sold. The pattern is systematic rather than alarmed, but the direction is uniform.
The street is divided on what the print will reveal. Bears, led by Wells Fargo which carries an Underweight with a $196 target, focus on slowing premium growth, rising loss ratios, and competitors whose rate increases are tapering off, reducing the competitive tailwind Progressive has enjoyed. KBW trimmed its target from $252 to $246 after the October print while keeping its Outperform rating, and Evercore moved its target modestly higher to $230 on November 3, maintaining In-Line. The mean price target from recent coverage sits around $232, fractionally below the current price of $235.78. At a trailing P/E of 14.3 and price-to-book of 3.5, the stock is not expensive by historical insurance standards, but the EPS momentum factor ranks in just the 18th percentile over both 30 and 90 days, a sign that forward estimates have been drifting lower.
Short interest has edged up about 5% over the past month to 7.27 million shares, a move worth noting as context rather than a signal on its own given the low absolute level. The official FINRA figure put days-to-cover at 3.5 as of October 30. Among peers, Progressive's one-week gain of 3.5% compares well, though ERIE lagged at 0.6% while CB added 2.9%. The peer group has broadly held up, suggesting sector tailwinds are present but not universal.
Tuesday's release is therefore less a test of whether Progressive can grow and more a test of whether the loss ratio has stabilised enough to justify a stock trading above the analyst consensus target, with insider selling already priced into the narrative.
Against its peers
Shares moved +3.5% over the past week against a median of +2.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open PGR on ORTEX →How this article was generated
- Generated
- 15 Nov 2026, 04:04
- Data as of
- 15 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.