
WSM Shorts Retreat Before the Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
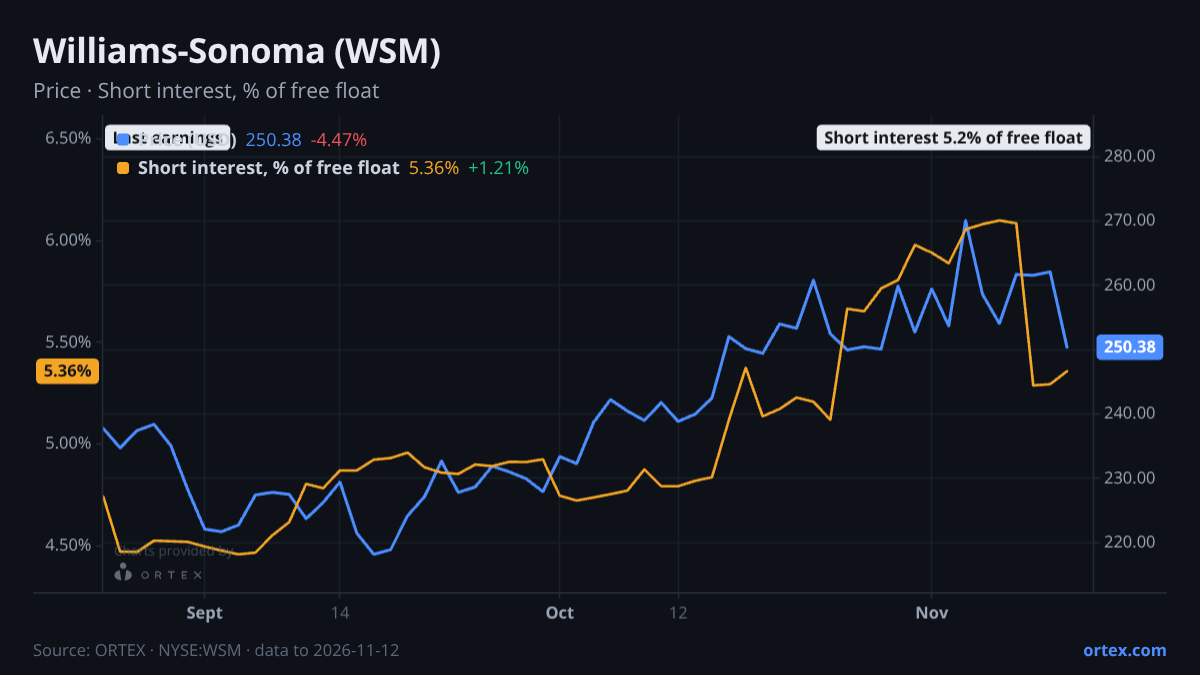
Williams-Sonoma reports Q3 results on November 18 with short sellers pulling back sharply from last week's elevated positioning.
Short interest fell 11.5% over the past week to 5.2% of the free float, reversing a portion of the 12% monthly build that had pushed the position to roughly one in nineteen tradeable shares. The retreat is statistically meaningful: the weekly change is 2.3 standard deviations below the company's typical weekly move. Despite the cover, the monthly build means more shares remain short today than at any point in October. Borrow conditions are loose, availability at 741%, meaning roughly seven shares sit available to borrow for every one already borrowed, leaving the lending market with no friction for either side. Cost to borrow has risen 36% over the past week but remains low in absolute terms at 0.61%.
The stock itself barely moved over the period, closing at $254.05, essentially flat on the week while closest peers including FND fell 6.8% and the correlated peer group dropped a median of several percent. That relative resilience likely explains some of the short covering. Options positioning is marginally more defensive than usual, with the put/call ratio at 0.76 against a 20-day average of 0.72, a z-score of 1.3, well short of anything extreme.
The analyst debate centers on the pace of top-line growth rather than the margin story. UBS raised its target to $265 on November 12, maintaining Neutral, while Citigroup lifted to $275 the week before, also staying Neutral. Both moves push their targets above the current price, yet neither firm upgraded. Bulls point to seven consecutive quarters of positive comparable sales, B2B revenue growing 14.5% to around $317 million, and management's 2026 net revenue growth guidance of 4.7% to 7.2%. Bears counter that the downside scenario implies a revenue CAGR of only 4.3% through 2027, with EPS of $9.76 and operating margins that may not support the current multiple. The stock trades at 24.7 times earnings, a level that leaves little room for a guidance cut.
The November 18 print will test whether seven-quarter momentum holds against tariff and housing headwinds at a valuation where the Street's most recent moves are upgrades in price target with no change in conviction.
Against its own history
This week's change in short interest is 2.3 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved -0.0% over the past week against a median of +1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open WSM on ORTEX →How this article was generated
- Generated
- 15 Nov 2026, 04:06
- Data as of
- 15 Nov 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.