
CRM drops 9% in a week as BTIG cuts to $250 ahead of December earnings
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
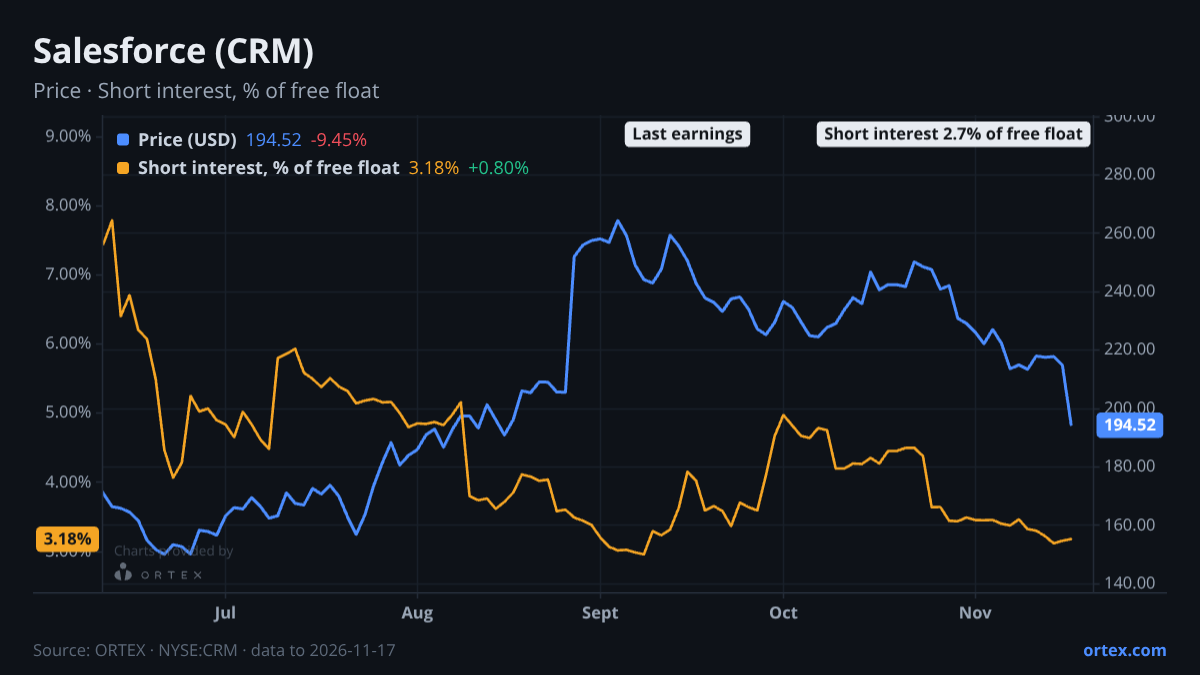
Salesforce fell 9.5% on Tuesday alone, taking the weekly loss to 8.9% and pushing the stock to $194.52, its worst single-day decline in months and a move that dwarfs the peer group median drop of 2.4% over the same period.
The catalyst sharpening attention this week is fresh analyst action. BTIG maintained its Buy rating on Wednesday but slashed its price target from $300 to $250, a 17% cut that lands with the stock already down 19% over the past month. That target still sits nearly 29% above Tuesday's close, which tells you something about how far the stock has moved in a short time. The broader Street backdrop has been more constructive: Bank of America upgraded to Buy from Underperform in mid-October with a $285 target, and several firms including Stifel and Freedom Broker raised targets following the August earnings release. The consensus mean target remains around $287, implying the sell-side still sees material recovery potential from current levels, but the direction of travel this week is clearly downward revision.
Short positioning offers little comfort or alarm to either camp. Short interest has actually eased over the past month, falling roughly 24% from late October highs to 2.66% of free float, a low absolute level for a large-cap name. Borrow conditions remain loose: availability is at 3,442%, meaning there is far more supply in the lending pool than demand from short sellers. Cost to borrow is 0.48%, up around 18% on the week but still trivially cheap. The options market is similarly unremarkable: the put/call ratio is 0.99, barely above its 20-day average of 0.98, and only 0.36 standard deviations outside normal range. None of these signals point to a crowded short or a squeeze setup. The selling pressure this week looks like long liquidation, not short conviction.
The bear case the Street is debating centres on execution risk and valuation ceiling. Management reiterated rather than raised its FY30 $63 billion revenue framework at the last update, which left little room for positive surprise. The proposed $5.7 billion Braze acquisition and the earlier $8 billion Informatica deal have added capital allocation uncertainty. Agentic AI is cited as both an opportunity and a disruption risk: rivals could use the same AI wave to attack Salesforce's stronghold in marketing automation and customer service. On the bull side, Agentforce and Data ARR reached $3.9 billion, up 210% year on year, cRPO grew 14% in Q2, and the Braze deal is expected to contribute over $1 billion of subscription revenue in FY29. The EV/EBITDA multiple has compressed to 9.3x and PE to 13.5x, both down materially over 30 days, so the stock is cheaper than it was. Factor scores are mixed: EPS momentum over 30 days ranks in just the 24th percentile, while the 90-day reading sits at the 71st, reflecting the sharp recent deterioration in near-term estimates versus a still-solid medium-term trend.
The peer comparison is worth isolating. ADBE fell 4.2% on the day but only 0.5% on the week. HUBS dropped 6.8% on Tuesday but is actually up nearly 10% on the week, suggesting company-specific rather than sector-wide pressure on CRM. NOW lost 6.5% on the day and 6.7% on the week, making it the closest peer in terms of weekly damage, though even that is around 2 percentage points less than Salesforce's decline. The insider register adds little signal here: recent Form 4 filings are exclusively option exercises (transaction code M) and tax withholding sales (code F), compensation mechanics rather than discretionary conviction trades.
The specific date to watch is December 2, when Salesforce reports its next quarter. Historical reactions have been volatile in both directions: the August 2026 print produced a one-day gain of 22.5% and a five-day gain of nearly 25%, while the September event produced a one-day loss of 5% and a five-day loss of 7%. With the stock already down almost 20% over the past month going into that release, and Wikipedia attention running nearly two standard deviations below its own 90-day average as of early November, the question is whether the next print revives the August dynamic or confirms the more recent pessimism baked into Tuesday's move.
Against its peers
Shares moved -8.9% over the past week against a median of -2.4% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open CRM on ORTEX →How this article was generated
- Generated
- 18 Nov 2026, 19:05
- Data as of
- 18 Nov 2026, 19:02
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.