
AMAT Heads Into Earnings With Analysts Raising Targets and Options Turning Defensive
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
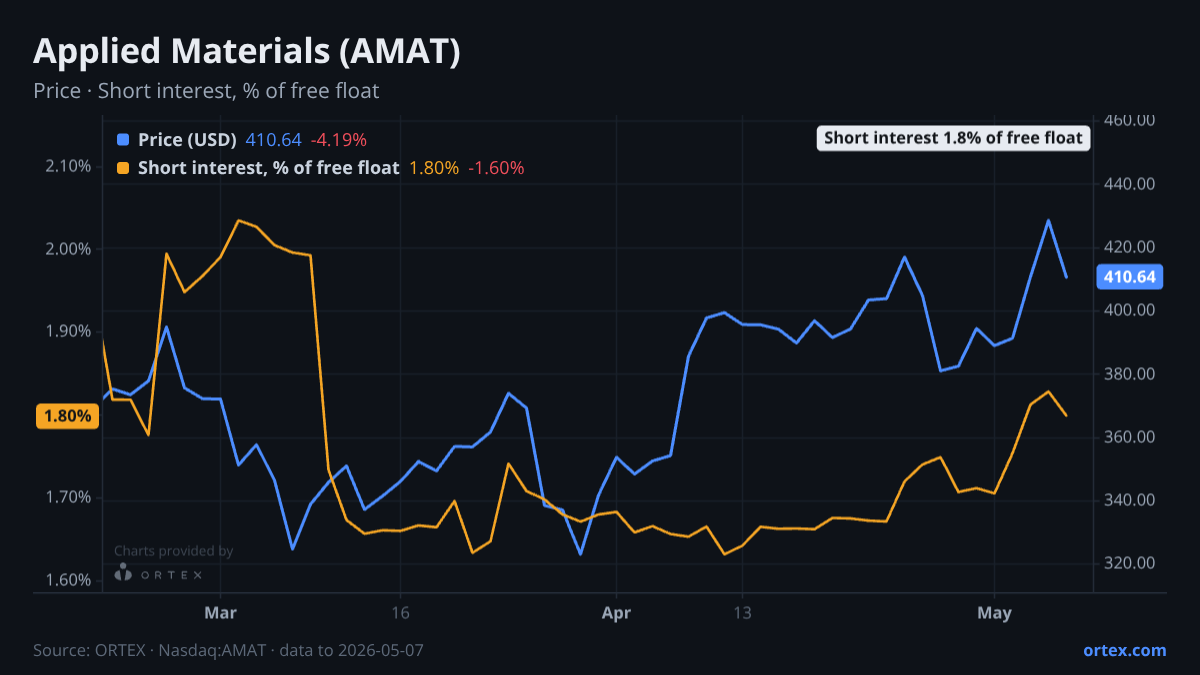
Applied Materials reports second-quarter results on May 14 with the stock up 23% over the past month — yet options traders are quietly building more protection than usual into the print.
The options signal is the sharpest data point in the setup. The put/call ratio has climbed to 1.08, nearly 1.8 standard deviations above its 20-day average of 1.00 — the most defensive reading in several months and approaching the 52-week high of 1.20. That hedging pressure has built even as the stock itself surged, gaining 6% in a single session on May 8 and nearly 12% on the week. The divergence is notable: the market is buying calls on one hand and puts on the other, reflecting genuine uncertainty about whether the rally holds through the print.
The short-selling community is not adding pressure here. Short interest is just 1.8% of the free float — a low base even after a 5% rise over the week. Borrow costs are negligible at 0.54%, and availability remains loose, with only a fraction of the lending pool in use against the 52-week peak of 2.53% utilization. There is no meaningful squeeze dynamic to speak of, and no evidence of a crowded short position building ahead of the release.
What's driving confidence — and caution simultaneously — is the analyst picture. The Street has been raising targets aggressively. Morgan Stanley lifted its price target to $454 from $432 last week while maintaining Overweight. UBS moved to $480 from $430, also reiterating Buy. HSBC initiated coverage with a Buy and a $517 target on May 8 — the most bullish call in the group. The consensus mean target of $438 sits roughly in line with the current price near $435, which means the market has already priced in much of the analyst optimism. Bulls point to AMAT's dominant position supplying foundry and logic chipmakers and its consistent record of beating estimates. Bears counter that the same customer concentration creates vulnerability: any shift in capex plans from the major foundries hits AMAT disproportionately, and at 35x trailing earnings, the valuation leaves limited room for disappointment.
Peers have broadly rallied alongside AMAT. LRCX gained 14.5% on the week, UCTT surged 16.7%, and KLAC added 8.3% — suggesting sector tailwinds rather than AMAT-specific re-rating. After the February print, the stock rose 4.4% on the day and extended gains to nearly 9% over the following five sessions. The May 14 report will test whether those tailwinds are durable enough to justify a stock that has now recaptured all the ground lost earlier this year — and whether the margin profile at current revenue levels can keep the bull case intact.
Against its own history
This week's change in short interest is 2.5 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +11.9% over the past week against a median of +9.2% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open AMAT on ORTEX →How this article was generated
- Generated
- 11 May 2026, 04:15
- Data as of
- 11 May 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signals
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.