
O'Reilly Options Tilt Bullish Into Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
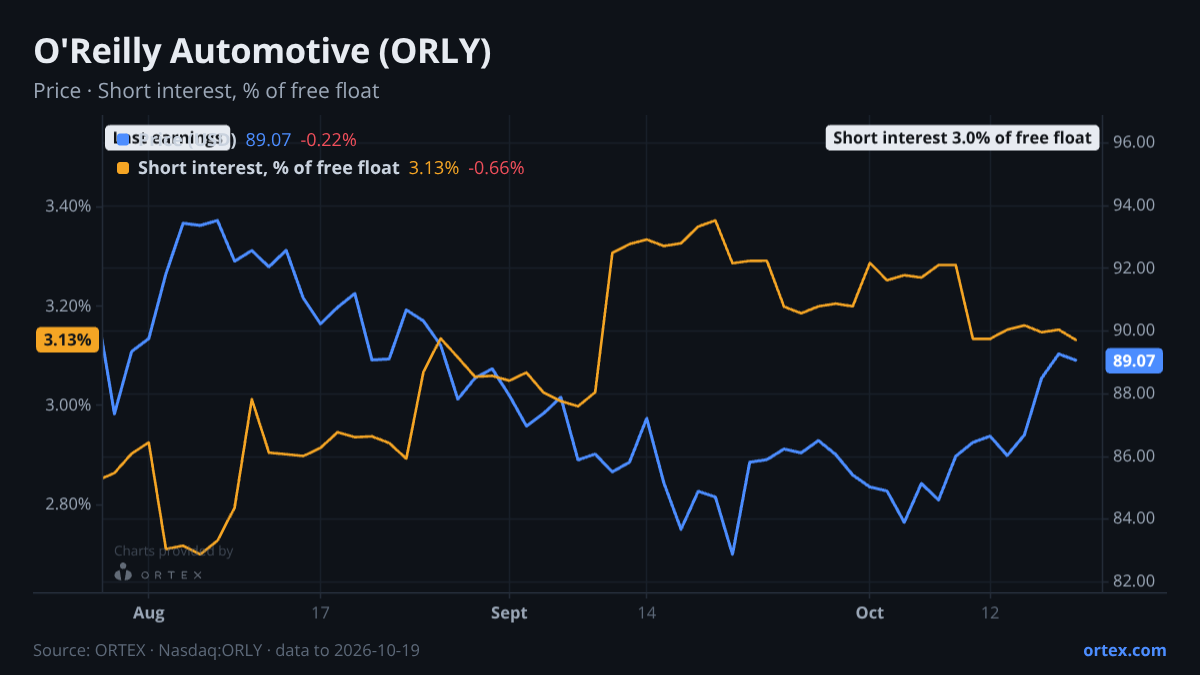
ORLY reports Q3 results after the close today with options traders positioned more bullishly than at almost any point in the past year.
The put/call ratio has dropped to 0.45, more than one standard deviation below its 20-day average of 0.51. That reading is close to the 52-week low of 0.41, meaning call volume is dominating the options market at an unusually high rate. The stock itself has recovered well, up 4.6% over the past week to $90.02, trimming a year-to-date loss that stood near 9% as recently as late September. The borrow market adds no friction to this picture: availability is effectively unlimited at roughly 9,300%, and cost to borrow runs at 0.51%, though that is up 40% over the past month from a low base. Short interest, at 3% of the free float and down nearly 6% over the past month, is not a meaningful factor on either side.
The analyst community is broadly constructive, though with some nuance. RBC Capital lifted its target to $111 yesterday, maintaining Outperform, and most buy-side targets cluster in the $106 to $114 range. Bernstein's initiation at Market Perform with a $94 target last month represents the cautious end of the range, essentially flagging fair value near current levels. The bull case rests on O'Reilly's distribution network, a 49/49 split between DIY and professional customers, and a track record of comparable-store growth in nine of the past eleven years. Bears point to macro sensitivity: management has previously indicated gas prices would need to hold well above $4 to drive meaningful demand uplift, while tariffs could push through price increases that weaken unit volumes across the nearly 6,600-store footprint. Private-label concentration at 55% of sales adds margin risk if competitive pricing intensifies.
Worth noting beyond the immediate print: ORTEX puts the probability of ORLY joining the CRSP US Mid index at 60% in the December 2026 Quarterly Review. That would require the stock to close above $93.66, roughly 5.2% above Tuesday's close. If inclusion is confirmed at the December 7 announcement, index trackers would need to buy an estimated $696 million worth of shares by December 22. That mechanical flow is a separate tailwind entirely from the earnings outcome.
Closest peer AZO gained 6.9% on the week against ORLY's 4.6%, and AAP rose 4.9%, with LOW and HD both up more than 5.5%. ORLY's recovery is real but it is lagging the group. The earnings history reinforces caution about the immediate reaction: the past three prints all produced a negative one-day move, ranging from minus 1.4% to minus 4.2%, before recovering over the following week. The Q3 release will test whether the distribution moat and professional mix hold margins steady enough to justify a valuation at 25 times trailing earnings, in a macro environment where the company's own management has been measured about demand conditions.
Against its peers
Shares moved +4.6% over the past week against a median of +6.1% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ORLY on ORTEX →How this article was generated
- Generated
- 21 Oct 2026, 04:08
- Data as of
- 21 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataIndex Rebalance
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.