
O'Reilly Short Sellers Retreat Before Q3 Results
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
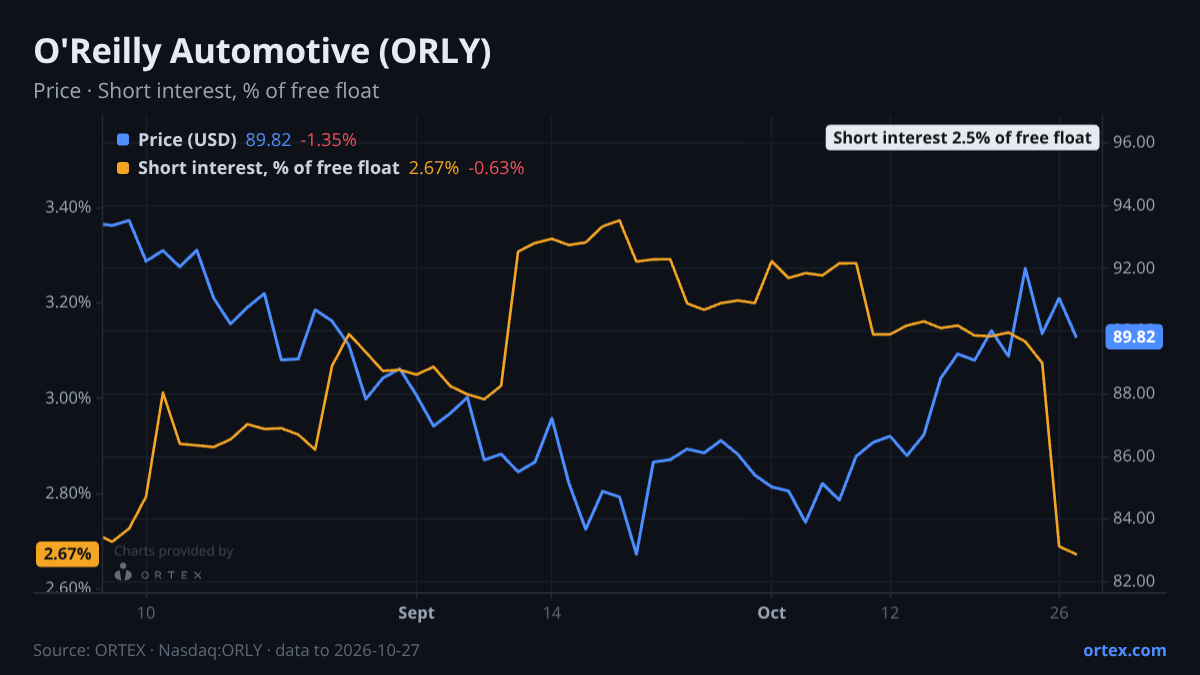
ORLY enters today's Q3 print with its peer group carrying heavier short-side positioning, making the auto parts retailer one of the less crowded names in its corner of retail. Short interest on O'Reilly now stands at 2.5% of the free float, well below the levels seen at closest peer AZO, and down 15% over the past week, a move 2.2 standard deviations below O'Reilly's typical weekly swing over the past year.
That unwind has been swift and consistent. Positions peaked above 26 million shares in early October and have dropped to roughly 21.4 million, with the sharpest step change coming in the final week. The borrow market reflects zero strain: availability is effectively unlimited, with hundreds of shares available for every one currently borrowed. Cost to borrow is 0.35%, down sharply over the past week. Together, these readings describe a short base that is retreating on its own terms rather than being squeezed out. Options corroborate the relaxed tone. The put/call ratio is 0.46, a touch below its 20-day average of 0.49, sitting near the lower end of the past year's range and consistent with the picture that emerged before last week's delayed print.
The analyst community's posture has not changed materially since the previews published earlier this week. Eighteen buy ratings sit against a consensus target of $106.65, implying roughly 18% upside from $90.44. Evercore ISI trimmed its target to $110 from $115 on Monday while holding Outperform, and that move fits the pattern seen after last July's results, when Morgan Stanley cut from $112 to $108 and TD Cowen from $117 to $110, both without dropping their positive ratings. The Street is still constructive but has spent three months quietly reducing what it is willing to pay. Bernstein's Market Perform initiation at $94 in late September anchors the cautious end and captures the bear case: tariff-driven supply chain costs hitting retail margins at a moment when consumer employment conditions may be softening. The bull camp points to distribution density advantages, professional sales at nearly half of revenue, and the expectation of 2026 comps in the 5% to 6% range as structural offsets.
Goldman Sachs Asset Management added over 1.6 million shares in the most recent disclosed period and T. Rowe Price added just over one million, two of the more notable institutional moves among the top holders. Retail attention, measured by Wikipedia page views against O'Reilly's own 90-day history, carried a z-score of 2.1 as of October 19, its highest reading in several months, suggesting a pickup in broader interest ahead of the release.
The print will test whether the gap between the still-bullish analyst consensus and the moderating price targets reflects disciplined caution or a more fundamental reset of what the business is worth at current margins.
Against its own history
This week's change in short interest is 2.2 standard deviations below the company's typical weekly move over the past year.
Against its peers
Shares moved +1.4% over the past week against a median of +1.3% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ORLY on ORTEX →How this article was generated
- Generated
- 29 Oct 2026, 04:30
- Data as of
- 29 Oct 2026, 04:07
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataIndex RebalancePrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.