
Wayfair Shorts Climb 24% in a Month, Co-Founders Sell
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
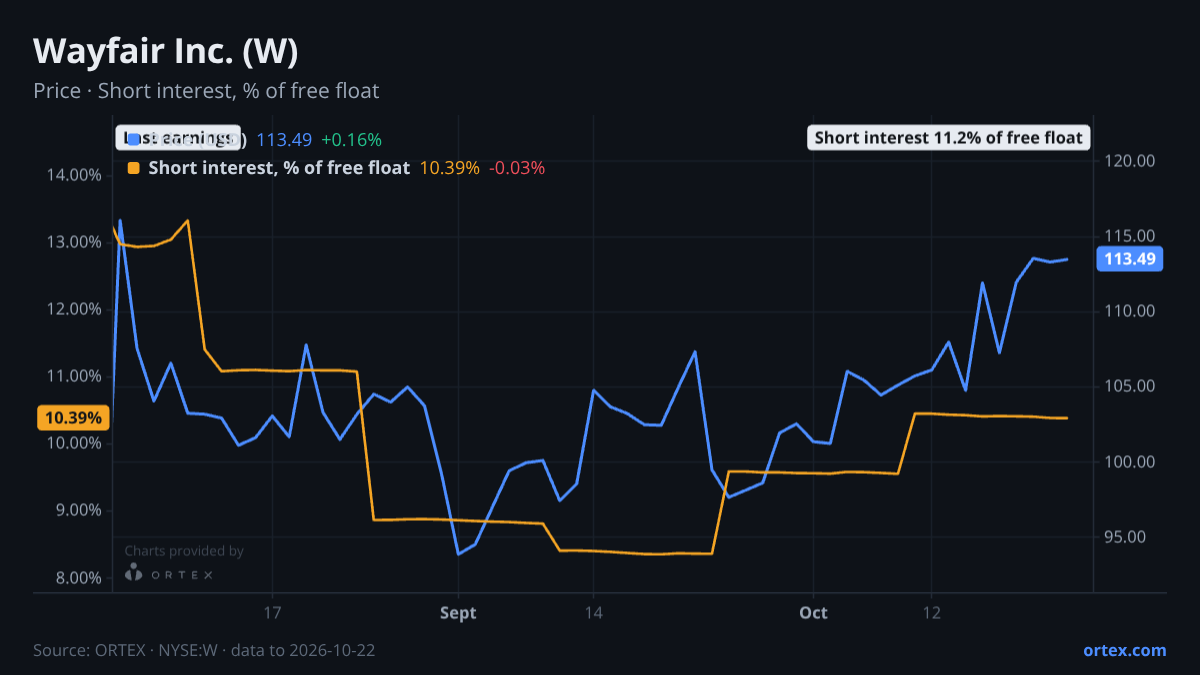
Short positioning in W has built steadily while the stock itself has drifted higher, creating an unusual gap between bearish conviction in the lending market and price momentum. Home furnishings peer WSM carries a higher short interest burden, and FND has outpaced Wayfair on the week (up 5.7% against W's 4.9%), but the month-over-month build in Wayfair shorts is the most pronounced in the group. Short interest now represents 11.2% of the free float, up 24% over the past month to roughly 11.9 million shares, though it has flattened in the past week. Despite that, the lending market remains wide open: availability runs at 4,476% of outstanding short interest, meaning shares to borrow are abundant and borrowing costs have actually eased, dropping to 0.40% from around 0.50% a week ago. Options positioning is similarly undemanding, with a put/call ratio of 0.86, almost exactly in line with its 20-day average and well below the 52-week high of 1.44.
The analyst community has been nudging targets higher into the print. RBC lifted its target to $96 on Thursday, while Piper Sandler raised to $135 earlier in the week, both maintaining their existing ratings. The consensus mean target is $122.89 against a current price of $112.49, implying a modest premium the market has not yet granted. The debate turns on margin trajectory. Bears point to the risk of gross margins slipping below 30% later in the year and same-store sales guidance of 4-6% trailing consensus expectations, alongside pressure from rising competition and AI disruption in e-commerce. The bull case rests on repeat customer orders growing to 8.8 million, an adjusted EBITDA margin of 5.1% in the most recent quarter, and a cash position of $1.54 billion that provides balance-sheet cover even as debt sits at $3.2 billion.
The most concrete signal ahead of Wednesday's print comes from inside the company itself. Co-founders Niraj Shah and Steven Conine each sold roughly $13 million worth of shares on October 15, all under pre-arranged 10b5-1 trading plans and therefore reflecting scheduled disposals rather than discretionary conviction. Over the past 90 days, total insider net selling reached approximately $57.9 million across 538,570 shares. These are plan-driven sales and may say little about near-term outlook, but their scale, spread across the CEO, a co-founder director, and the CTO, is notable context for a stock trading near a multi-month high. The institutional register shows FMR as the largest external holder at 11.9% and Capital Research at 8.2%, with Capital World's 13G showing a stake trimmed from 12.7% to 9.7% as of August.
The last earnings release in early August produced a one-day move of more than 20%, the print before that a decline of roughly 5%. The range of historical reactions is wide, which makes the relatively calm options market positioning worth noting: traders have not priced in the kind of tail protection that the previous August move might have prompted. Wednesday's report will test whether the margin recovery story has enough momentum to justify a stock that has risen nearly 5% this month against a short base that has grown even faster.
Against its peers
Shares moved +4.9% over the past week against a median of +4.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open W on ORTEX →How this article was generated
- Generated
- 26 Oct 2026, 04:26
- Data as of
- 26 Oct 2026, 04:01
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.