
Guardant Health Analysts Lift Targets Before Q3 Print
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
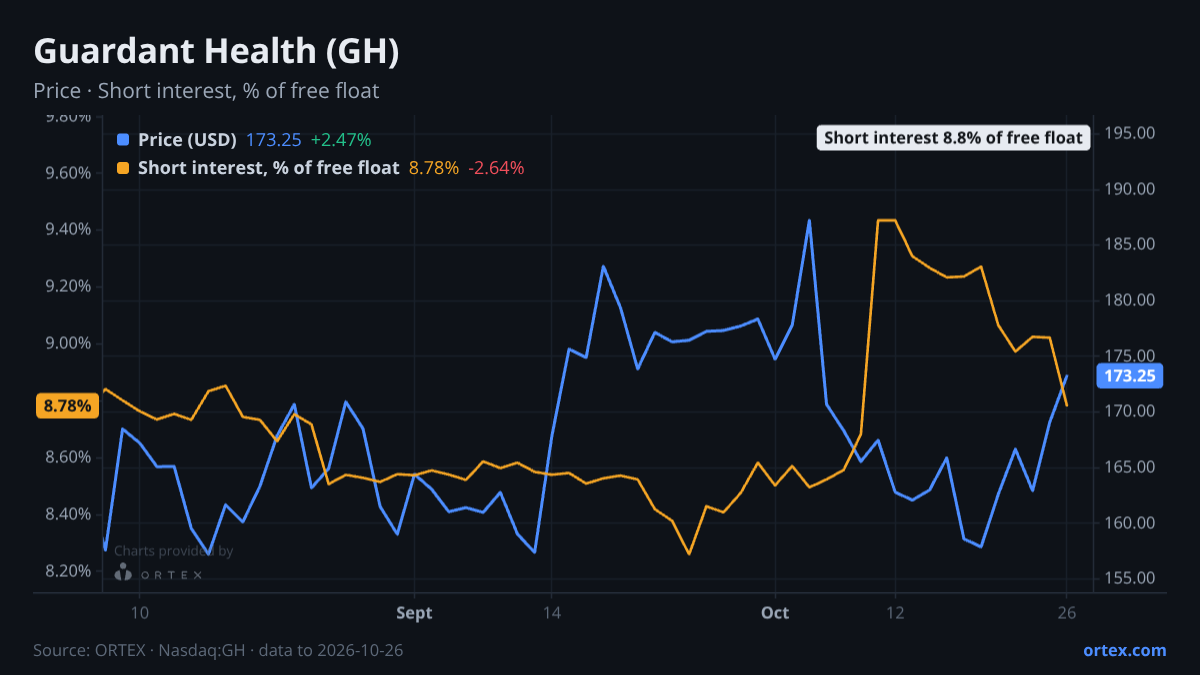
GH gained 9.5% last week to $178.06, outpacing a peer median of 2.9%, with the move pulling the stock to within 12% of the consensus price target of $202.24. Short interest at 8.8% of the free float is meaningful but retreating: shorts are down 4.9% over the week to about 11.4 million shares, the lowest level in a month, with borrowing costs running at just 0.46% and availability vastly in excess of demand. The put/call ratio at 1.10 is nearly flat against its 20-day average of 1.11, a z-score of minus 0.19, which points to options positioning that is neither defensive nor speculative. Nothing in the lending market or the derivatives book signals elevated conviction on either side.
The analyst story is more directional. Morgan Stanley raised its target to $200 from $185 on October 13, keeping an Overweight rating. Barclays had already moved to $220 from $200 on October 7. Roth Capital initiated at Buy with a $200 target last week. These moves point to a Street that has been lifting estimates ahead of the print rather than hedging. The bull case centres on Q1 2026 revenue of $302 million, up 48% year over year, the August 1 UnitedHealthcare coverage decision for Shield, and ACS and NCCN guideline inclusion for liquid biopsy tests. Management raised full-year guidance to $1.30 to $1.32 billion. The bear case is harder to dismiss: Guardant360 still generates more than 60% of sales, so any deceleration from 30% volume growth would quickly change the calculus. Cash burn exceeded $200 million in each of the past two years, and the MRD competitive environment has intensified. The company's own forward earnings revisions rank in the 95th percentile of the universe, which goes some way to explaining why the stock is up 55% year to date, but it also tightens the margin for error on Thursday.
Institutional flows add one more layer. FMR (Fidelity) added 1.33 million shares in the quarter to September 30, and Columbia Management added 1.74 million shares in the same period. T. Rowe Price added 755,000. Against that, recent insider activity has been dominated by routine option exercises and tax-withholding sales rather than discretionary open-market moves, and the net 90-day insider position across the Form 4 register is effectively flat in value terms. Wikipedia attention has spiked to a z-score of 2.1 against the stock's own 90-day history, a sign of rising retail interest ahead of the report.
The last quarterly print, in July, produced a 12.4% one-day gain and an additional 9.4% over the following five days. That outcome was against a comparably positioned stock: short interest elevated, borrow cheap, analysts broadly constructive. The question Thursday's release will answer is whether Shield's commercial ramp into the second half of 2026 and the trajectory of Guardant360 volume growth are enough to justify the multiple expansion the analyst community has already started to price in.
Against its peers
Shares moved +9.5% over the past week against a median of +2.9% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open GH on ORTEX →How this article was generated
- Generated
- 28 Oct 2026, 04:40
- Data as of
- 28 Oct 2026, 04:03
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.