
Arista Shorts Jump 25% in a Week After Earnings Pop
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
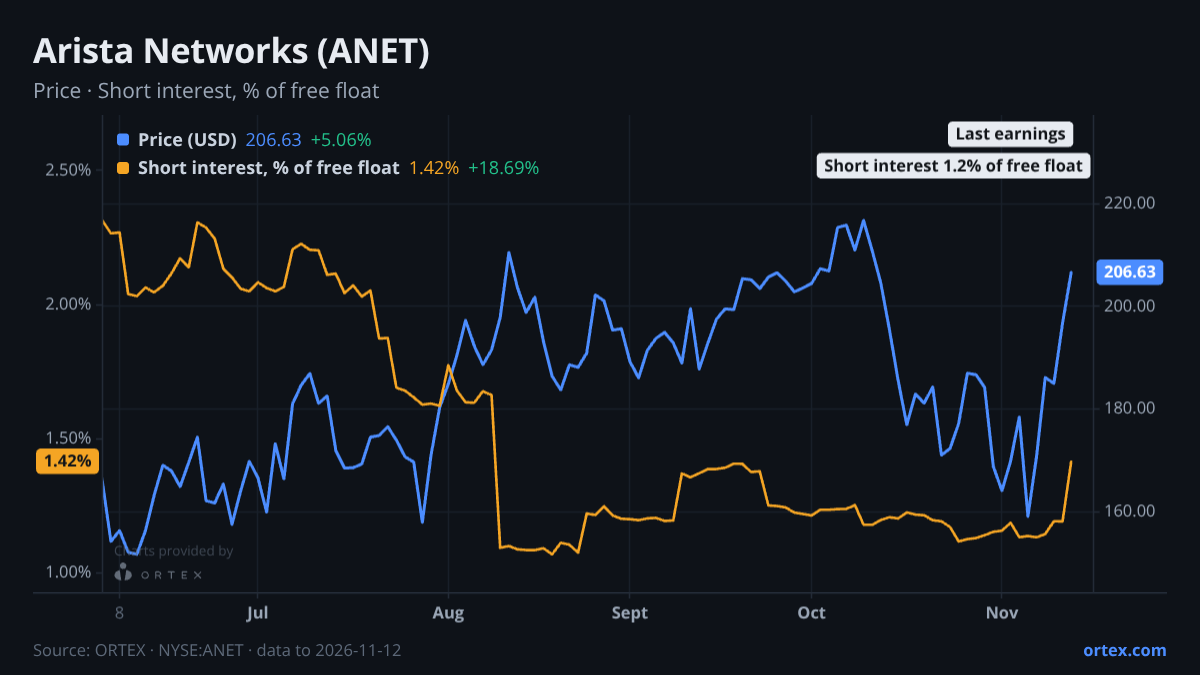
Arista Networks gained 15.5% in the past week, one of the sharpest moves in its peer group, yet short interest rose 25% over the same period. That divergence is the clearest tension in the data right now.
The short position rebuild is unusually sharp. At 1.18% of the free float, the absolute level remains low, but the week-on-week increase of roughly 25% is 2.8 standard deviations above Arista's typical weekly move over the past year. The jump is concentrated in a single session: shares short climbed from 12.6 million on November 11 to 14.9 million on November 12, an 18.7% one-day move. That looks like fresh positioning after the Q3 earnings-driven rally rather than a gradual accumulation. The borrow market is not under pressure. Availability is extremely loose at over 7,000%, meaning there is vastly more lending supply than current short demand, and cost to borrow at 0.52% is negligible. Short sellers are adding exposure without paying a premium to do it.
Options positioning is broadly neutral. The put/call ratio at 0.96 is slightly below its 20-day average of 0.97, with a z-score of roughly -0.5. That puts it well inside the 52-week range of 0.73 to 1.05. Options traders are not driving incremental caution or conviction here; the signal is quiet relative to the sharp move in shares short. The ORTEX short score edged up to 30.6 on November 12, its highest reading in the trailing 10 sessions, consistent with the short interest build, but still a low absolute level for a large-cap stock.
The Street is broadly constructive, with most of the analyst activity concentrated around the November 4 Q3 print. UBS raised its target to $291, JP Morgan went to $270, and Morgan Stanley lifted to $230, all while maintaining positive ratings. Barclays moved in the opposite direction, cutting from $289 to $236 despite keeping its Overweight. Wells Fargo also trimmed slightly. The mean price target across the coverage sits at $249.65, roughly 27% above the November 13 close of $197.29. The bull case rests on 58.5% year-on-year revenue growth in Q3, management guidance for FY27 revenue around $18.5 billion, and AI Fabric revenue on track to roughly double. Bears point to gross margin pressure risk as silicon, memory and optics costs inflate, and to customer concentration: Microsoft and Meta are outsized drivers of quarterly results. EPS momentum factor scores are strong at 91 on the 30-day measure and 81 on the 90-day, while the valuation factors are demanding. The trailing PE is 35.5 and the EV/EBITDA multiple has risen roughly 1.1 points over the past week as the stock rallied.
The insider data adds one important footnote. Andreas Bechtolsheim, the 10% owner and co-founder, sold roughly 314,000 shares across November 5 and 6, with transactions totalling close to $44 million at prices from $162 to $172. All sales were under a pre-arranged 10b5-1 plan, so they represent scheduled rather than discretionary activity. His net reduction across the past 90 days is around 1 million shares worth $179 million. Bechtolsheim remains Arista's largest individual shareholder at 14.2% of shares outstanding, with BlackRock at 7.2% and Vanguard close behind. Capital Research added over 14.5 million shares in the most recent reported period, the largest single institutional move among the top holders.
Peer moves over the past week reinforce how sector-wide the networking and optical infrastructure rally has been. CIEN gained 15.3% and LITE added 10.8%, both closely correlated with Arista. Friday's reversal was similarly broad: Arista fell 4.5%, CIEN dropped 4.6%, and VIAV fell 5.6% on the same session. The co-movement suggests the weekly gain was largely driven by macro or sector rotation rather than Arista-specific catalysts beyond the Q3 results.
The next scheduled earnings event is February 12, 2027, 90 days away. Between now and then, the question is whether the short interest rebuild at elevated prices after the Q3 pop reflects durable new conviction or tactical positioning that fades as the stock consolidates. The pace at which that 14.9 million share short position either grows further or gets covered against the $249 consensus target is the specific level worth watching.
Against its own history
This week's change in short interest is 2.8 standard deviations above the company's typical weekly move over the past year.
Against its peers
Shares moved +15.5% over the past week against a median of +4.6% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open ANET on ORTEX →How this article was generated
- Generated
- 14 Nov 2026, 20:15
- Data as of
- 14 Nov 2026, 20:05
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt Data
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.