
COHR Shorts Surge at Two-Standard-Deviation Pace as CEO Buys the Dip
Produced automatically from ORTEX data and published under the ORTEX News editorial standards set by Peter Hillerberg, Editor, ORTEX News. How we publish
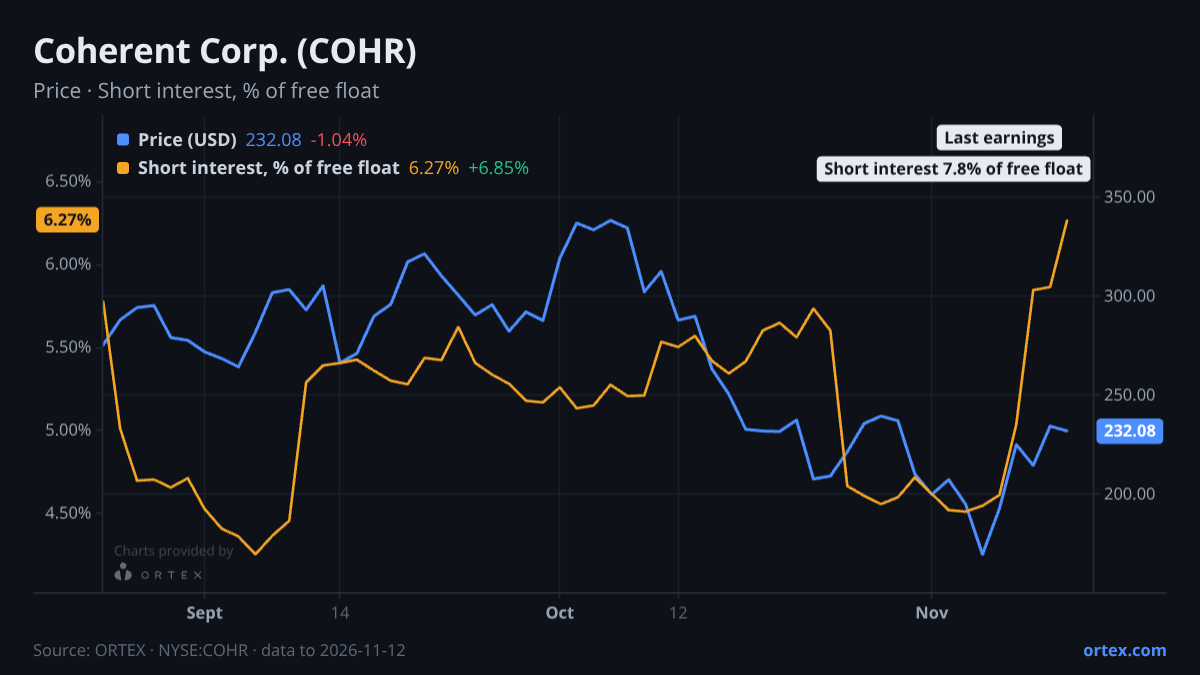
Among Coherent Corp.'s closest peers, short positioning looks notably more crowded than the group: closest correlate FN fell 7.3% on the day while peers like AEIS and SANM gained 11.5% and 17.5% on the week, yet Coherent's short interest has climbed to 7.8% of free float, the highest in at least a year, while peer shorts remain far less elevated.
That build has been unusually fast. Short interest jumped 39% in a single week, a move running 2.2 standard deviations above Coherent's typical weekly change. From early November the borrowed share count has risen from roughly 8.8 million to 12.3 million. The speed of that build is striking given the stock simultaneously rallied 13% on the week. Shorts are adding into strength, not into a falling price. Borrow cost remains cheap at 0.53%, offering no friction to new entrants, and availability at over 1,000% means the lending pool is far from stressed, so the build is conviction-driven rather than a squeeze-forced covering event.
What makes the picture unusual is the concurrent insider behaviour. CEO James Anderson bought 5,000 shares at $199.48 on November 9, spending just under $1 million in a discretionary open-market purchase with no 10b5-1 plan attached. Director Enrico Digirolomo followed with a further 1,000 shares at $222.89 on November 10. Both trades came after the stock had already fallen roughly 25% over the prior month, and they sit against a 90-day net insider position that remains negative at approximately minus $7 million, mostly reflecting tax-withholding transactions by other officers. The CEO purchase, however, is a pure open-market buy with no compensation mechanics behind it.
Analysts are broadly still constructive but have been trimming targets aggressively. Citigroup raised its target to $440 on November 6, the one outlier moving higher. Needham, Morgan Stanley, Susquehanna and TD Cowen all cut targets in the weeks prior, with Morgan Stanley at $325 and TD Cowen at $275 sitting well below the consensus mean of $372. The bull case centres on Coherent's PhotonLink optical interconnect franchise, a reported $20 billion long-term agreement, and 79% year-on-year revenue growth in the most recent quarter. Bears point to net debt near $1.66 billion, negative free cash flow of roughly $1 billion last fiscal year, and $2.6 billion in inventory. That tension explains both the short build and the CEO's decision to step in personally.
Historical earnings reactions add further texture. The November 2026 print produced a 32.7% single-day gain. The one before that fell 18.2%. The stock has swung hard in both directions in recent quarters. The November 18 print will test whether the capacity ramp and margin trajectory justify the gap between the current price of $218 and analyst targets clustered between $275 and $440, and whether the CEO's bet at $199 reflected information or simply a floor call that shorts have already decided to challenge.
Against its own history
This week's change in short interest is 2.2 standard deviations above the company's typical weekly move over the past year. Short interest is at its highest level in at least a year.
Against its peers
Shares moved +13.1% over the past week against a median of +6.7% for its closest peers.
Stocks in this article
See the live data behind this article on ORTEX.
Open COHR on ORTEX →How this article was generated
- Generated
- 15 Nov 2026, 04:06
- Data as of
- 15 Nov 2026, 04:00
- Prompt version
- v1.0
- Data sources
- Short interestCost to borrowUtilizationOptions flowEarningsAnalyst consensusInstitutional positioningORTEX Alpha signalsRecent ORTEX notesAlt DataPrevious Mi Articles
ORTEX Market Intelligence content is generated by AI from a snapshot of ORTEX's proprietary data and reviewed by the ORTEX team. Content is informational only and does not constitute investment advice.